U.S. Bank Altitude Reserve Card: New Updates Explained
Major changes to the U.S. Bank Altitude Reserve Visa Infinite Card are now in effect, including a lower 1-cent-per-point standard travel redemption value, a $5,000-per-billing-cycle cap on 3x mobile-wallet purchases, and tighter restrictions on the card’s $325 annual travel credit. However, existing cardholders have also gained higher earning rates for travel booked through the U.S. Bank Travel Center and, more recently, the ability to transfer points to select airline and hotel loyalty programs.
The changes substantially reshape a card that was historically popular for its simple combination of mobile-wallet rewards and flexible travel redemptions.
There is another important point for anyone considering the card: the U.S. Bank Altitude Reserve remains closed to new applicants. The changes therefore matter primarily to existing cardholders deciding how to earn and redeem Altitude points going forward.
Here is what changed, what remains, and how the Altitude Reserve works in 2026.
U.S. Bank Altitude Reserve Changes at a Glance
The major earning and redemption changes took effect on December 15, 2025, while transferable points arrived later, in August 2026.
| Benefit | Previous Structure | Current Structure |
| Mobile-wallet earning | 3x points without the current monthly cap | 3x on first $5,000 per billing cycle, then 1x |
| Travel redemption value | Up to 1.5 cents per point | Generally up to 1 cent per point for standard travel redemptions |
| $325 annual credit | Eligible travel and dining purchases | Eligible travel through U.S. Bank Travel Center |
| Travel Center hotels | Lower previous earning structure | 10x points on eligible prepaid hotels |
| Travel Center car rentals | Lower previous earning structure | 10x points on eligible prepaid car rentals |
| Travel Center flights | Lower previous earning structure | 5x points on eligible prepaid flights |
| Direct eligible travel | 3x | 3x |
| Transfer partners | Not previously available | Airline and hotel partners now available |
| New applications | Closed | Still closed |
That distinction matters because the Altitude Reserve’s current structure is the result of several updates rather than one single change.
1. Mobile-Wallet Purchases Now Have a 3x Spending Cap
Altitude Reserve cardholders still earn 3 points per $1 on eligible mobile-wallet purchases, but only on the first $5,000 spent each billing cycle. Purchases beyond that threshold earn 1 point per $1.
U.S. Bank currently defines qualifying mobile wallets for this benefit as:
- Apple Pay
- Google Wallet
- Samsung Pay
U.S. Bank specifically notes that Google Pay may not always qualify depending on how a transaction is completed.
This is one of the most important changes because mobile-wallet earning was historically one of the card’s defining advantages.
How Does the $5,000 Mobile-Wallet Limit Work?
The limit applies per billing cycle, not per calendar year.
For example, suppose a cardholder makes $6,500 in otherwise eligible mobile-wallet purchases during one billing cycle.
The earning would generally work like this:
- First $5,000: 15,000 points at 3x
- Remaining $1,500: 1,500 points at 1x
- Total: 16,500 points
Under the previous uncapped structure, all $6,500 could have earned at the elevated mobile-wallet rate.
For cardholders who normally spend considerably less than $5,000 through mobile wallets each billing cycle, the practical impact may be limited. High spenders, however, need to monitor the cap more carefully.
2. Travel Purchases Still Earn 3x Points
One major earning category remains intact.
Altitude Reserve cardholders continue to earn 3 points per $1 on qualifying travel purchases made directly with eligible travel merchants.
U.S. Bank lists examples such as:
- Airlines
- Hotels
- Car rental companies
- Taxicabs
- Limousines
- Passenger trains
- Cruise lines
Merchant coding determines whether a transaction qualifies.
U.S. Bank does not control the merchant category code assigned by Visa, so simply thinking of a purchase as “travel” does not automatically guarantee 3x earnings.
3. U.S. Bank Travel Center Hotels and Car Rentals Now Earn 10x
Cardholders now earn 10 points per $1 on qualifying prepaid hotel and car rental reservations booked through the U.S. Bank Travel Center and paid for with the Altitude Reserve card.
That consists of:
- 1 base point
- 9 bonus points
This is substantially higher than the card’s standard 3x travel earning rate.
However, there is an important distinction.
Prepaid hotels and car rentals booked through the Travel Center are not treated as ordinary 3x travel-category transactions. Instead, they earn according to the Travel Center’s separate 10x structure.
Should You Automatically Book Hotels Through the Travel Center?
Not necessarily.
The 10x rate is attractive, but travelers should still compare:
- Direct hotel prices
- Travel Center prices
- Cancellation terms
- Hotel loyalty benefits
- Elite-night eligibility
- Hotel points earning
- Property-specific promotions
A higher credit-card earning rate does not always make a third-party booking the better overall deal.
4. Travel Center Flights Now Earn 5x
Prepaid flights booked through the U.S. Bank Travel Center and paid for with the Altitude Reserve card now earn 5 points per $1.
The earning structure consists of:
- 1 base point
- 4 bonus points
Again, Travel Center flight reservations are handled separately from the standard 3x travel category.
A traveler purchasing a qualifying flight directly from a carrier can generally earn 3x, while an eligible prepaid flight purchased through the U.S. Bank Travel Center can earn 5x.
Before choosing the portal solely for 2 additional points per dollar, compare pricing, change rules, and booking-management options.
5. Altitude Reserve Points Lost Their Old 1.5-Cent Travel Value
One of the most consequential changes is the removal of the Altitude Reserve’s old 1.5-cents-per-point travel redemption rate. Standard travel redemptions now generally provide a maximum value of 1 cent per point.
Under the previous structure:
10,000 points × 1.5 cents = $150 in travel
At 1 cent each:
10,000 points × 1 cent = $100 in travel
That represents a $50 reduction in value for every 10,000 points redeemed this way.
For 50,000 points, the difference becomes:
| Redemption Rate | Value of 50,000 Points |
| 1.5 cents each | $750 |
| 1 cent each | $500 |
| Difference | $250 |
This significantly changes the effective return of the card’s earning categories.
Previously, earning 3x and redeeming at 1.5 cents per point could effectively produce up to 4.5 cents of travel value per dollar spent.
At a straightforward 1-cent redemption value, 3x is equivalent to 3 cents of redemption value per dollar.
Actual value can now vary when transferring points to loyalty partners.
6. Real-Time Rewards Is Less Valuable for Travel
Real-Time Rewards remains available, but the former 1.5-cent travel redemption advantage is gone.
Real-Time Rewards allows enrolled cardholders to redeem points against eligible purchases by responding to a text message after completing a qualifying transaction.
The process generally works like this:
- Enroll in Real-Time Rewards.
- Select eligible purchase categories and preferences.
- Make a qualifying purchase.
- Receive a redemption text.
- Reply REDEEM within the permitted period.
- Points are deducted and a statement credit is applied.
U.S. Bank says Real-Time Rewards texts are available only for transactions with U.S. merchants. Travel purchases must also be made directly with qualifying travel providers.
The current rules set minimum purchase amounts of $150 for lodging and $150 for car rentals.
7. The $325 Annual Credit Is Much More Restrictive
The Altitude Reserve still provides up to $325 in annual travel statement credits, but qualifying purchases must now be made through the U.S. Bank Travel Center.
Previously, the credit was much easier to use because it covered broad travel and dining purchases.
That meant ordinary purchases could trigger the benefit without requiring travelers to change how they booked.
The new structure is more restrictive.
Cardholders now need to deliberately use the U.S. Bank Travel Center for eligible travel if they want to capture the full $325 benefit.
Why Does This Change Matter?
The Altitude Reserve carries a $400 annual fee for existing cardholders.
Using the full $325 travel credit can substantially offset that cost:
$400 annual fee – $325 travel credit = $75
But that calculation only works for a cardholder who would naturally use the entire $325 credit at close to face value.
If portal prices are higher than booking directly, or if a cardholder would not otherwise make an eligible Travel Center booking, treating the credit as a full $325 of personal value may overstate its usefulness.
8. Altitude Reserve Now Has Transfer Partners
The most significant positive development came later in 2026.
U.S. Bank introduced airline and hotel transfer partners for eligible Altitude Reserve cardholders in August 2026.
As of September 2026, current transfer options include:
| Transfer Partner | Transfer Ratio |
| Air France-KLM Flying Blue | 1:1 |
| Avianca LifeMiles | 1:1 |
| Ethiopian Airlines ShebaMiles | 1:1 |
| Qantas Frequent Flyer | 1:1 |
| ALL – Accor Live Limitless | 2:1 |
The first 4 airline programs receive transfers at 1 U.S. Bank point to 1 airline mile, while Accor uses a 2:1 ratio.
U.S. Bank’s current program rules confirm that eligible cardholders may transfer points to participating travel loyalty programs through the Rewards Center. Partner programs and ratios can change.
Are Point Transfers Reversible?
No.
U.S. Bank states that loyalty-program transfers are final and irrevocable once submitted. Most transfers are expected to process by the next business day, although U.S. Bank says they can take up to 72 hours.
Therefore, check:
- Award availability
- Required number of miles
- Taxes and fees
- Transfer ratio
- Loyalty-program account details
before moving points.
9. Transfer Partners Could Provide More Than 1 Cent per Point
The new transfer feature creates an alternative to redeeming points directly at 1 cent each.
Suppose a cardholder transfers 30,000 Altitude points at 1:1 to an eligible airline program.
Those points become 30,000 airline miles.
The eventual value then depends on the award booked rather than U.S. Bank’s fixed 1-cent travel redemption rate.
This does not mean every transfer is automatically better.
An award with high taxes, poor availability, or an unfavorable mileage price could provide less value than a simple cash-equivalent redemption.
Transfers are most useful when a cardholder has identified a specific loyalty redemption and calculated its value beforehand.
10. Existing Cardholders Still Receive Priority Pass Access
Altitude Reserve cardholders continue to receive Priority Pass Select membership with a limited number of complimentary visits rather than unlimited lounge access.
The benefit currently provides 8 visits per Priority Pass membership year. Those visits can be used by the cardholder or applied toward guests, subject to the program’s applicable rules.
This structure differs from premium cards that provide unlimited Priority Pass visits.
Travelers who regularly use airport lounges should therefore track how many visits remain rather than assuming lounge entry is unlimited throughout the year.
Enrollment may be required before the benefit can be used.
11. The Card Remains Closed to New Applicants
The U.S. Bank Altitude Reserve remains unavailable to new applicants in 2026.
U.S. Bank stopped accepting new applications in November 2024, but existing cardholders have generally been able to keep using their accounts.
That creates an unusual situation.
U.S. Bank has continued modifying and expanding a rewards program attached to a card that consumers cannot currently apply for.
The addition of transfer partners in August 2026 is particularly notable because the feature arrived nearly 2 years after new applications closed.
There is no verified indication in the current sources that U.S. Bank plans to reopen Altitude Reserve applications, so travelers should not assume the card will become publicly available again.
What Does the Altitude Reserve Earn Now?
Here is the current earning structure for existing cardholders:
| Purchase | Points per $1 |
| Prepaid hotels through U.S. Bank Travel Center | 10x |
| Prepaid car rentals through U.S. Bank Travel Center | 10x |
| Prepaid flights through U.S. Bank Travel Center | 5x |
| Eligible direct travel purchases | 3x |
| Eligible mobile-wallet purchases, first $5,000 per billing cycle | 3x |
| Mobile-wallet purchases above $5,000 in same billing cycle | 1x |
| Other eligible purchases | 1x |
One detail is worth noting when a purchase qualifies as both travel and mobile wallet.
U.S. Bank says bonus points are not stacked. The transaction receives one applicable bonus treatment, with mobile wallet applied ahead of travel in the points hierarchy.
Altitude Reserve: What Got Better and What Changed?
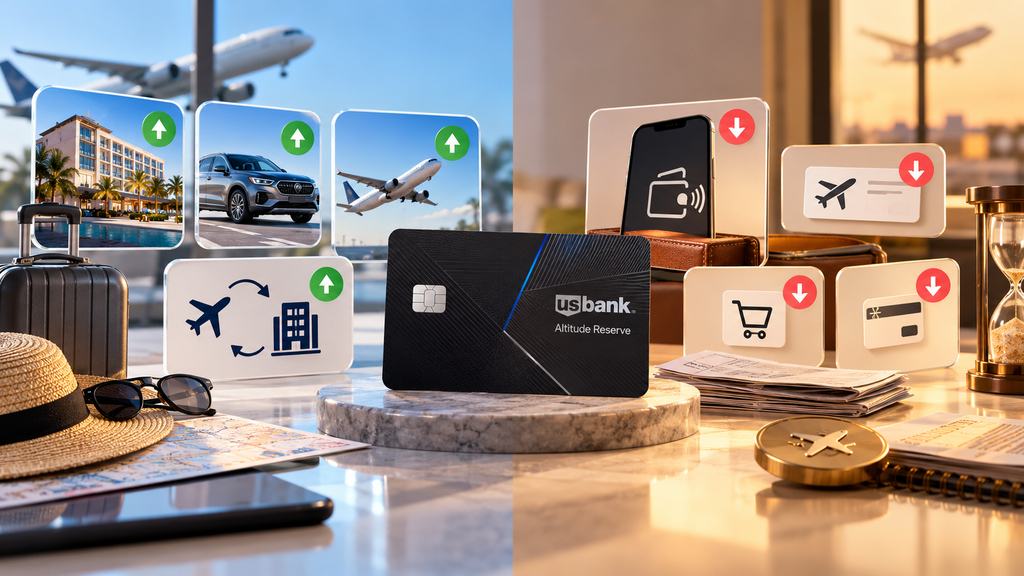
The update is not entirely one-directional.
Newly Added or Improved Features
- 10x on qualifying prepaid hotels through the Travel Center
- 10x on qualifying prepaid car rentals through the Travel Center
- 5x on qualifying prepaid flights through the Travel Center
- Airline and hotel transfer partners
- 3x on eligible direct travel remains intact
Benefits That Became More Restrictive
- 3x mobile-wallet purchases capped at $5,000 per billing cycle
- Standard travel redemption value reduced from 1.5 cents to 1 cent per point
- $325 annual credit restricted to qualifying Travel Center purchases
- Real-Time Rewards lost the old elevated travel redemption value
The practical impact therefore depends on how an existing cardholder uses the card.
Someone who regularly transfers points or books portal travel may interact with the new structure very differently from someone who primarily valued unlimited 3x mobile-wallet spending and simple 1.5-cent Real-Time Rewards redemptions.
What Existing Cardholders Should Check
Existing Altitude Reserve cardholders should review how they use the card under the new rules rather than relying on its historical benefits.
Pay particular attention to:
- Your mobile-wallet spending each billing cycle
- Whether you can naturally use the $325 Travel Center credit
- Direct versus portal travel prices
- Loyalty benefits potentially lost on portal hotel bookings
- Available transfer partners
- Award availability before transferring points
- Remaining Priority Pass visits
- Your annual-fee renewal date
It is also worth checking the U.S. Bank Rewards Center periodically because participating transfer partners and redemption options are subject to change.
Conclusion
The U.S. Bank Altitude Reserve looks substantially different from the card existing members originally signed up for. Its former combination of uncapped 3x mobile-wallet earnings, easy-to-use travel and dining credit, and 1.5-cent travel redemptions has been significantly restricted.
At the same time, the current version introduces a different rewards strategy: 10x prepaid hotels and car rentals through the Travel Center, 5x prepaid Travel Center airfare, and transfers to airline and hotel loyalty programs.
For existing cardholders, the important step is to evaluate the card based on the current rules rather than its former benefits. Pay particular attention to whether you can naturally use the $325 portal-based travel credit, stay within the mobile-wallet bonus cap, and make productive use of the new transfer partners.
And for travelers who do not already hold the Altitude Reserve, the card remains closed to new applications as of September 2026.
Frequently Asked Questions
The largest changes include a $5,000-per-billing-cycle cap on 3x mobile-wallet spending, reduction of the standard travel redemption rate from 1.5 cents to 1 cent per point, and restriction of the $325 annual travel credit to eligible U.S. Bank Travel Center purchases. The card also gained 10x Travel Center hotel/car-rental earning, 5x Travel Center airfare earning, and loyalty-program transfers.
The major earning, credit, and redemption changes took effect on December 15, 2025. U.S. Bank subsequently launched point transfers in August 2026.
Yes. Eligible Apple Pay purchases can earn 3x points on the first $5,000 of qualifying mobile-wallet spending each billing cycle. Purchases beyond the $5,000 threshold earn 1x for that billing cycle.
Yes. Eligible travel purchases made directly with qualifying merchants continue to earn 3 points per $1.
No. The previous 1.5-cent travel redemption benefit ended. Standard travel redemptions now generally top out at 1 cent per point, although transferring points to a loyalty program can result in a different value depending on the eventual redemption.
Yes, but it is now more restrictive. The annual credit applies to qualifying travel purchases made through the U.S. Bank Travel Center rather than the card’s former broad travel-and-dining structure.
Yes. Eligible cardholders can now transfer points to participating airline loyalty programs. Current partners include Flying Blue, Avianca LifeMiles, Ethiopian ShebaMiles, and Qantas Frequent Flyer at 1:1.
Yes. ALL – Accor Live Limitless is currently a U.S. Bank transfer partner at a ratio of 2 Altitude points to 1 ALL point.
No. The Altitude Reserve remains closed to new applicants. U.S. Bank stopped accepting applications in November 2024.
The Altitude Reserve has a $400 annual fee for existing cardholders.
Yes. Existing cardholders can receive Priority Pass Select access with 8 complimentary visits per membership year, subject to the benefit’s terms and enrollment requirements.