Chase Ink Business Premier Card: Apply, Earn & Save Today
The Chase Ink Business Premier Credit Card is currently open for applications, offering business owners unlimited cash-back rewards, enhanced earnings on large purchases, and a $1,000 new cardmember bonus after meeting the qualifying spending requirement. The card carries a $195 annual fee and is designed particularly for businesses with substantial everyday or large-ticket expenses.
Cardholders can earn 2.5% cash back on purchases of $5,000 or more, 2% on other eligible business purchases, and 5% on travel purchased through Chase Travel. Unlike a traditional revolving business credit card, the Ink Business Premier combines a Pay in Full structure with Chase’s Flex for Business feature.
Here’s what business owners should know before applying.
Chase Ink Business Premier Credit Card at a Glance
The Ink Business Premier is positioned as a straightforward cash-back business card. Rather than requiring cardholders to keep track of multiple rotating spending categories, its reward structure focuses heavily on everyday business spending and high-value purchases.
| Card Feature | Current Details |
| Annual Fee | $195 |
| Welcome Offer | $1,000 bonus cash back |
| Welcome Offer Requirement | Spend $10,000 in first 3 months |
| Large Purchases | 2.5% cash back on purchases of $5,000+ |
| Other Business Purchases | Unlimited 2% cash back |
| Chase Travel Purchases | Unlimited 5% cash back |
| Flex for Business APR | 17.74%–28.49% variable APR |
| Employee Cards | Available at no additional cost |
Current offer and pricing information can change, so applicants should verify Chase’s terms immediately before applying.
What Is the Ink Business Premier Welcome Offer?
New Ink Business Premier cardmembers can currently earn $1,000 bonus cash back after spending $10,000 on purchases within the first 3 months after opening the account.
The spending requirement is substantial, so the welcome offer is particularly relevant to businesses that can reach the threshold through normal operating expenses rather than making unnecessary purchases solely to qualify for the bonus.
For example, a business expecting to purchase equipment, inventory, software, advertising, or other eligible business expenses shortly after opening the card may find it easier to meet the required spending threshold. Chase notes that the new cardmember bonus might not be available if you’ve previously had this card. The issuer may also consider other factors related to the business when determining bonus eligibility.
How Does the Ink Business Premier Earn Cash Back?
One of the card’s main attractions is its relatively simple reward structure.
2.5% Cash Back on Purchases of $5,000 or More
Cardholders receive 2.5% total cash back on every eligible purchase of $5,000 or more, with no stated earning cap on this category. This can be particularly valuable for businesses regularly making large purchases.
For example, a qualifying $10,000 purchase would generate $250 in cash back when redeemed, according to Chase.
A company frequently purchasing inventory, equipment, technology, or other expensive business necessities could therefore benefit more from this rate than a company whose expenses are primarily made up of small transactions.
2% Cash Back on Other Business Purchases
Eligible purchases below the $5,000 threshold generally earn unlimited 2% cash back.
This flat earning rate means cardholders do not have to continually determine whether an expense belongs to a particular bonus category.
Business owners could use the card for eligible expenses such as:
- Office supplies
- Business meals
- Advertising expenses
- Software subscriptions
- Inventory
- Professional services
- Equipment
- Other routine business purchases
Whether a transaction qualifies for rewards depends on Chase’s rewards-program terms.
5% Cash Back Through Chase Travel
The Ink Business Premier also earns unlimited 5% cash back on travel purchased through Chase Travel.
For a company that regularly books qualifying business travel through the Chase platform, this provides an opportunity to earn at a higher rate than the card’s standard 2% return.
Travelers should still compare prices and booking conditions before choosing a portal solely for additional rewards.
How Much Could a Business Earn With the Card?
The value of the reward structure depends considerably on how a business spends. Suppose a business makes an eligible $7,000 equipment purchase. At 2.5% cash back, that transaction would earn $175 in rewards.
If the same business makes $3,000 in other eligible purchases earning 2%, those purchases would generate another $60 in cash back. Businesses making frequent transactions of $5,000 or more have the greatest opportunity to benefit from the enhanced 2.5% earning rate.
Is the Ink Business Premier a Pay in Full Card?
Yes, the Ink Business Premier operates primarily as a Pay in Full card, but Chase also provides its Flex for Business feature.
Chase explains that purchases are automatically included in the Flex for Business balance until that assigned limit is reached. Purchases exceeding that limit are added to the Pay in Full balance, which must be paid each month. Amounts within the Flex for Business balance can be paid over time with interest.
The current Flex for Business variable APR is 17.74% to 28.49%, although the rate applicable to an individual cardholder depends on Chase’s terms and can change. That makes understanding which purchases fall into each balance particularly important before carrying debt.
What Benefits Come With the Ink Business Premier?
The Ink Business Premier provides more than its cash-back structure. Business owners also receive features intended to make company spending easier to manage.
Employee Cards at No Additional Cost
Businesses can add employee cards without an additional card fee. This can allow employees to make authorized purchases while helping the company centralize spending and earn rewards from eligible transactions. Chase also provides tools that can help businesses monitor employee spending.
Business Spending Management
Business owners can use account-management features to keep track of transactions and monitor spending. For companies with several employees making purchases, consolidating eligible expenses onto one business account may also simplify expense tracking.
Purchase and Account Protections
The card includes several protections and account-security features. The reference article highlights benefits including purchase protection, cell phone protection, extended warranty protection, fraud protection, and zero-liability protection. Specific limits, eligibility rules, exclusions, and claim requirements apply, so cardholders should review Chase’s applicable benefits documentation rather than assuming every purchase is covered.
How Do Ink Business Premier Rewards Work?
Although the card is marketed primarily around cash back, Chase explains that cash-back rewards under the program are tracked as points, with $1 in cash-back rewards equal to 100 points.
Rewards can be redeemed through Chase Ultimate Rewards. Chase currently advertises redemption possibilities including cash back, gift cards, travel, and other available options. However, business owners interested primarily in maximizing transferable travel rewards should carefully compare the Premier with other Chase business cards before applying.
Ink Business Premier vs. Ink Business Preferred
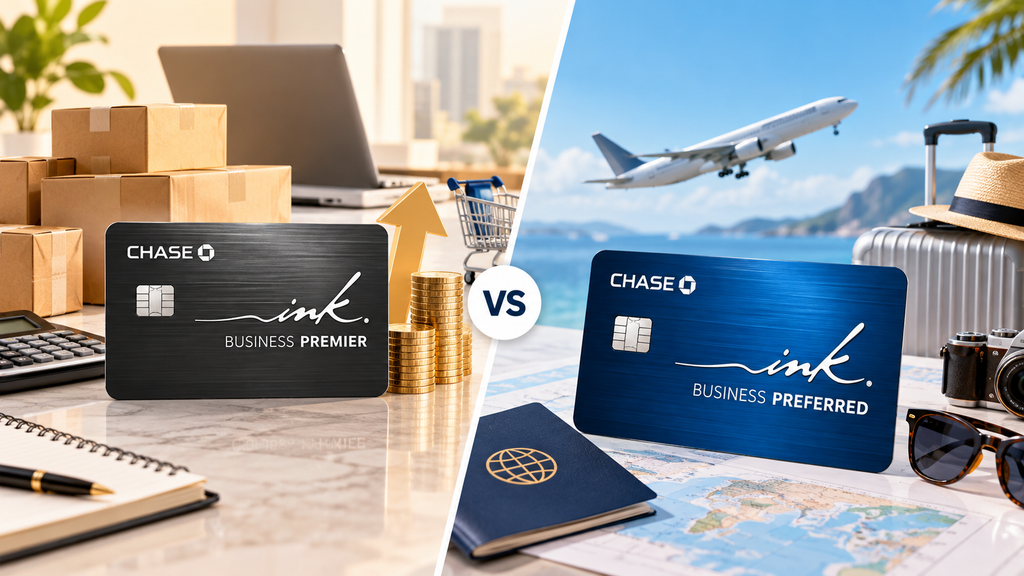
Despite their similar names, the Ink Business Premier and Ink Business Preferred target somewhat different spending patterns.
| Feature | Ink Business Premier | Ink Business Preferred |
| Annual Fee | $195 | $95 |
| Current Welcome Offer | $1,000 cash back after $10,000 spend in 3 months | 100,000 bonus points after $8,000 spend in 3 months |
| Main Earning Feature | 2.5% cash back on purchases of $5,000+ | 3x on eligible travel and business categories, up to applicable combined spending limit |
| Other Spending | 2% cash back | Depends on category |
| Primary Appeal | Straightforward cash back and large purchases | Points and business/travel categories |
Current Chase information shows that the Ink Business Preferred earns 3x on qualifying travel and business categories on up to $150,000 in combined spending under the applicable terms.
The Premier may therefore attract businesses seeking straightforward cash-back earnings, particularly those regularly making purchases worth at least $5,000. The Preferred has a different rewards structure and includes access to point transfers to participating frequent-travel programs. The better fit depends on how a particular business spends and plans to redeem its rewards.
Who Can Benefit From the Ink Business Premier Card?
The Ink Business Premier’s reward structure is particularly relevant to businesses with high spending and frequent large transactions.
Potential users may include businesses that:
- Regularly make individual purchases of $5,000 or more.
- Prefer cash-back rewards over complicated bonus categories.
- Spend significantly on ordinary business expenses.
- Can naturally satisfy the welcome bonus requirement.
- Want employee cards without an additional card fee.
- Prefer to pay most business expenses in full each month.
- Purchase eligible travel through Chase Travel.
However, the $195 annual fee means applicants should estimate the value they expect to receive from the card rather than focusing only on its headline earning rates.
What Should You Consider Before Applying?
Before submitting an application, compare the card against your company’s actual spending habits. First, consider how often your business makes purchases of at least $5,000. The 2.5% rate is one of the card’s distinguishing rewards features, so businesses making primarily smaller purchases may receive less value from this particular advantage.
Second, consider the $195 annual fee. A card’s rewards and benefits should provide enough practical value for your business to justify its ongoing cost. Third, evaluate whether your business can meet the $10,000 spending requirement within 3 months for the current $1,000 welcome bonus without increasing spending unnecessarily.
Finally, understand the Pay in Full and Flex for Business structure before using the card for expenses you expect to finance.
How to Apply for the Chase Ink Business Premier
The Ink Business Premier is currently available for applications directly through Chase. The issuer allows prospective cardholders to sign in before applying or continue with an application as a guest.
Before starting an application, business owners should have the required personal and business information available and carefully review the latest offer details, pricing, APR, eligibility requirements, and cardmember agreement. Credit approval is not guaranteed, and terms can change.
Is the Chase Ink Business Premier Worth Considering?
The Ink Business Premier can be worth considering for businesses with high annual expenses and frequent purchases of $5,000 or more, particularly when straightforward cash-back rewards are more useful to the company than managing multiple spending categories.
Its combination of 2.5% cash back on qualifying purchases of $5,000 or more, unlimited 2% on other eligible business purchases, 5% through Chase Travel, and a current $1,000 welcome bonus creates a reward structure focused on higher-spending businesses.
The $195 annual fee, spending requirements, Pay in Full structure, and applicable APR should all be weighed against the rewards a particular business realistically expects to earn.
Final Thoughts
The Chase Ink Business Premier is built around a relatively straightforward proposition: businesses can earn elevated cash back without managing numerous bonus categories. The strongest feature is the 2.5% cash-back rate on individual purchases of $5,000 or more, supplemented by 2% on other eligible purchases and 5% through Chase Travel.
Businesses considering the card should look beyond the welcome bonus and calculate whether their normal spending is high enough to make the rewards worthwhile after accounting for the $195 annual fee. Most importantly, review Chase’s latest application offer and pricing terms immediately before applying because bonuses, APRs, and other card terms can change.
Frequently Asked Questions
Yes. Chase currently accepts applications for the Ink Business Premier online.
The current annual fee is $195.
New cardmembers can currently earn $1,000 bonus cash back after spending $10,000 on purchases during the first 3 months after account opening, subject to Chase’s eligibility and offer terms.
No. The 2.5% cash-back rate applies to eligible individual purchases totaling $5,000 or more. Other eligible purchases generally earn 2%.
Yes. Cardholders currently earn 5% cash back on travel purchased through Chase Travel.
Yes. Employee cards are available at no additional cost, according to Chase.
The card primarily uses a Pay in Full structure while providing Flex for Business for eligible balances up to an assigned limit. Flex balances can be paid over time with interest.
Chase currently lists a 17.74%–28.49% variable APR for Flex for Business. Rates and terms can change, so applicants should verify them before applying.