Travel Insurance Guide: Coverage & Common Exclusions
Travel insurance can protect travelers against certain financial losses caused by covered problems before or during a trip, including cancellations, interruptions, medical emergencies, delays, lost baggage, and emergency evacuation. However, coverage varies substantially by policy, and standard travel insurance does not reimburse every unexpected travel problem.
The most important words to understand are “covered reason.” Most benefits apply only when the event causing your loss meets the policy’s definitions, conditions, and limits.
For example, a policy may cover trip cancellation when a traveler becomes seriously ill before departure, but it generally will not reimburse someone who simply changes their mind about taking the trip unless qualifying Cancel for Any Reason coverage applies.
That makes reading the policy documents just as important as comparing the premium.
This guide explains the main types of travel insurance, common benefits and exclusions, travel medical coverage, Cancel for Any Reason protection, credit card insurance, claims, and what to check before purchasing a policy.
Key Overview: Travel Insurance Coverage
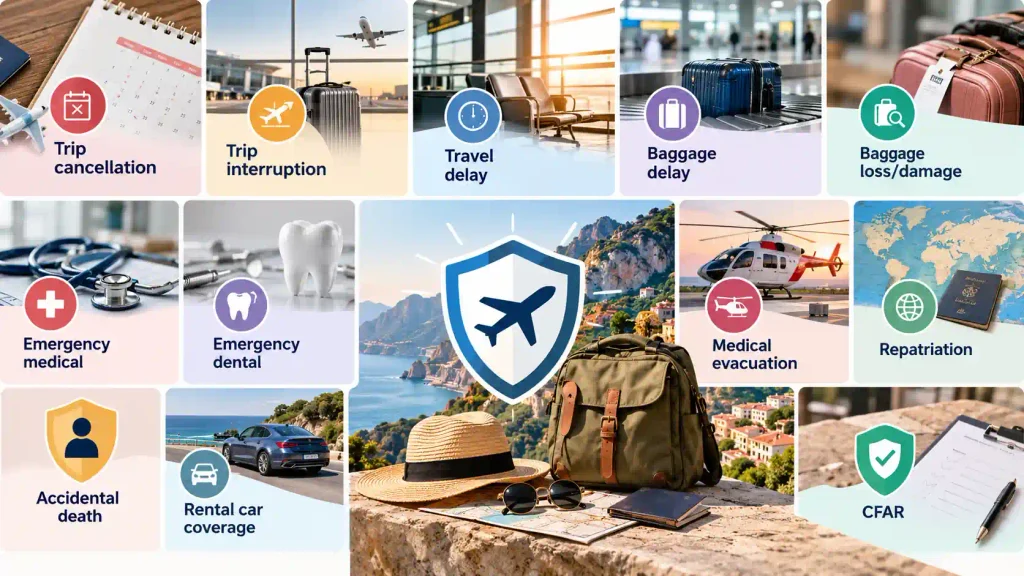
| Coverage | What It May Cover |
| Trip cancellation | Prepaid, nonrefundable costs after a covered cancellation |
| Trip interruption | Certain unused trip costs and additional transportation after a covered interruption |
| Travel delay | Eligible expenses caused by a qualifying delay |
| Baggage delay | Essential purchases when baggage is delayed |
| Baggage loss/damage | Covered lost, stolen, or damaged belongings |
| Emergency medical | Eligible medical treatment during the trip |
| Emergency dental | Qualifying emergency dental treatment |
| Medical evacuation | Transportation to appropriate medical care |
| Repatriation | Covered transportation following a qualifying medical event or death |
| Accidental death | Benefit following certain covered accidents |
| Rental car coverage | Eligible damage or theft, depending on the policy |
| CFAR | Partial reimbursement for many otherwise uncovered cancellation reasons |
Coverage, benefit limits, deductibles, exclusions, and definitions differ between policies.
What Is Travel Insurance?
Travel insurance is coverage designed to reduce certain financial risks associated with traveling.
A comprehensive policy may combine several benefits into one plan, including protection for:
- Trip cancellation
- Trip interruption
- Travel delays
- Missed connections
- Baggage problems
- Emergency medical expenses
- Emergency medical evacuation
- Travel assistance
Travel insurance is not a promise that every financial loss associated with a trip will be reimbursed.
Instead, the policy establishes:
- What events are covered.
- What expenses qualify.
- How much the insurer will pay.
- What documentation is required.
- What exclusions apply.
- When the policy must be purchased.
- How and when a claim must be submitted.
Two policies marketed as “comprehensive travel insurance” can therefore provide very different protection.
What Are the Main Types of Travel Insurance?
Travel insurance can be divided into several broad categories.
Comprehensive Travel Insurance
A comprehensive plan generally bundles several protections together.
Depending on the policy, this might include:
- Cancellation
- Interruption
- Delay
- Baggage
- Medical emergencies
- Evacuation
- Assistance services
This type of plan can be useful for travelers with substantial prepaid, nonrefundable trip costs who also want protection during the journey.
Travel Medical Insurance
Travel medical insurance focuses primarily on medical costs incurred while traveling.
This can be particularly important for international travel.
The U.S. Department of State recommends checking how your existing health insurance works overseas before departure. It notes that Medicare and Medicaid generally do not pay for medical care outside the U.S., while private insurance coverage abroad varies by plan.
Travel medical insurance may cover qualifying:
- Doctor visits
- Hospital treatment
- Emergency services
- Prescription medication
- Emergency dental care
- Medical transportation
Do not assume your domestic health insurance automatically follows you internationally.
Medical Evacuation Insurance
Medical evacuation coverage helps pay eligible transportation expenses when a traveler needs to be moved to an appropriate medical facility.
This can become particularly important in:
- Remote destinations
- Islands
- Cruise itineraries
- Adventure trips
- Areas with limited medical facilities
The U.S. Department of State says air-ambulance evacuation back to the U.S. can cost roughly $20,000 to $200,000, depending on location and medical circumstances.
A policy’s evacuation benefit should therefore be evaluated separately from its ordinary emergency medical limit.
What Does Trip Cancellation Insurance Cover?
Trip cancellation insurance can reimburse eligible prepaid, nonrefundable expenses when you cancel before departure for a reason specifically covered by your policy.
Potential covered reasons vary.
Examples found in some policies include:
- Serious illness
- Covered injury
- Death of a traveler or qualifying family member
- Natural disaster affecting a destination
- Certain employment termination
- Jury duty
- Certain legal obligations
- Destination becoming uninhabitable
The exact requirements matter.
For example, merely feeling too unwell to travel may not automatically satisfy a medical cancellation benefit. A policy may require documentation from a physician or impose other conditions.
Similarly, bad weather somewhere near your destination does not necessarily qualify as a covered cancellation.
Always check the actual policy language.
What Is Trip Interruption Insurance?
Trip interruption coverage applies after a trip has already begun and can reimburse certain expenses when a covered event forces the traveler to cut the journey short or change plans.
Suppose you are halfway through a 10-day vacation when a qualifying family emergency requires you to return home.
Depending on the policy, trip interruption benefits could help with:
- Unused prepaid arrangements
- Additional transportation
- Changes needed to return home
Trip cancellation and trip interruption are therefore related but different.
Cancellation = before departure
Interruption = after the trip begins
Benefit limits and covered reasons vary by policy.
How Does Travel Delay Insurance Work?
Travel delay coverage can reimburse certain reasonable expenses when a covered delay lasts long enough to meet the policy’s minimum requirement.
Eligible expenses may include:
- Meals
- Accommodation
- Local transportation
- Essential purchases
Imagine your qualifying flight delay requires an unexpected overnight stay.
If your policy’s conditions are met, it might reimburse eligible hotel and meal expenses up to the applicable daily and overall limits.
But a 1-hour delay may not qualify if the policy requires a much longer waiting period.
Check:
- Minimum delay requirement
- Covered causes
- Per-day limit
- Maximum benefit
- Required documentation
Keep receipts whenever you incur expenses you might later claim.
What Does Baggage Insurance Cover?
Baggage coverage can provide reimbursement for eligible belongings that are lost, stolen, damaged, or delayed during a trip.
Travel insurance policies may separate baggage protection into 2 categories.
Baggage Loss or Damage
This benefit can reimburse covered belongings when they are permanently lost, stolen, or damaged.
Policies commonly have:
- Overall baggage limits
- Per-item limits
- Special limits for valuables
- Excluded items
Do not assume a $2,000 baggage benefit means a $2,000 laptop will automatically be fully reimbursed.
Individual-item limits may apply.
Baggage Delay
Baggage delay insurance is different.
It may reimburse essential purchases when checked luggage does not arrive within the policy’s specified period.
Qualifying purchases might include basic:
- Clothing
- Toiletries
- Personal necessities
This is not generally permission to replace the entire contents of your suitcase.
Reasonable expenses and policy limits still apply.
Does Travel Insurance Cover Medical Emergencies?
Many comprehensive travel insurance plans include emergency medical coverage, but limits, deductibles, exclusions, and whether coverage is primary or secondary can vary.
Travelers should check:
- Medical benefit limit
- Deductible
- Emergency dental limit
- Pre-existing condition rules
- Destination restrictions
- Adventure activity exclusions
- Primary versus secondary coverage
- Payment procedures
Some overseas hospitals may require payment before treatment or before discharge.
The State Department advises travelers to find out whether their policy can make payments directly to overseas hospitals and whether 24-hour assistance is available.
Primary vs. Secondary Medical Coverage
This distinction can affect how a claim is handled.
Primary Coverage
Primary travel medical insurance generally allows an eligible claim to be submitted to the travel insurer without first seeking payment from another applicable health insurer, subject to the policy terms.
Secondary Coverage
Secondary coverage may require the traveler to submit eligible expenses to another insurer first.
The travel insurer may then consider remaining covered expenses.
Read the policy carefully because claim procedures differ.
What Is Emergency Medical Evacuation?
Emergency medical evacuation coverage can pay eligible transportation costs when adequate medical treatment is not available where the traveler becomes ill or injured.
That does not necessarily mean the traveler gets to choose any hospital or request a private flight home.
Policies may require the insurer or assistance provider to:
- Approve the evacuation.
- Determine medical necessity.
- Select an appropriate medical facility.
- Coordinate transportation.
This distinction is important.
“Medical evacuation” may mean transportation to the nearest appropriate facility, not automatically transportation back to your home.
Check whether the policy also provides repatriation or transportation home under specified circumstances.
What Is Cancel for Any Reason Travel Insurance?
Cancel for Any Reason, commonly called CFAR, is optional protection available with some travel insurance policies that can reimburse part of your insured trip cost when you cancel for a reason that standard cancellation coverage does not include.
CFAR is broader than normal trip cancellation coverage, but it is not literally unlimited.
The National Association of Insurance Commissioners notes that CFAR can add close to 50% to the total travel insurance cost.
Common CFAR structures can also involve:
- Buying coverage soon after the initial trip deposit
- Insuring the required amount of prepaid trip costs
- Canceling before a specified deadline
- Receiving only partial reimbursement
For example, traditional CFAR plans commonly reimburse around 50% to 75% of eligible prepaid expenses rather than 100%.
Specific requirements vary by insurer and jurisdiction.
Standard Trip Cancellation vs. CFAR
Travelers should read the CFAR endorsement itself rather than relying on the product name.
| Feature | Standard Cancellation | CFAR |
| Cancellation reason | Must generally be covered by policy | Much broader |
| Reimbursement | Subject to policy benefit | Usually partial |
| Additional cost | Included in applicable plan | Usually costs extra |
| Purchase deadline | Policy-specific | Often time-sensitive |
| Cancellation deadline | Policy-specific | Usually before scheduled departure |
| Availability | Common | Not available with every plan or everywhere |
What Does Travel Insurance Usually Not Cover?
Travel insurance contains exclusions, and the exact exclusions depend on the policy.
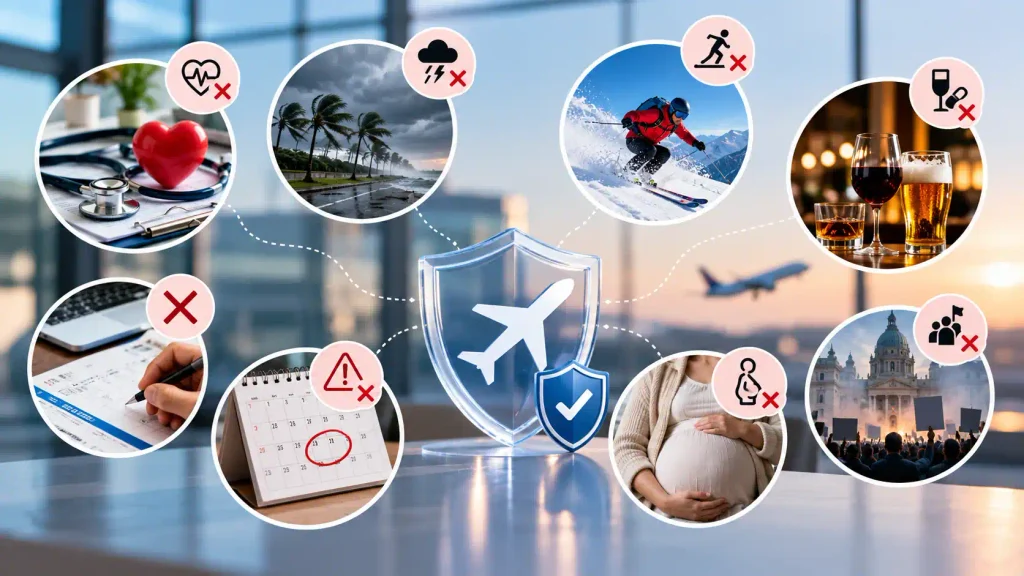
The NAIC identifies several common examples that travelers may encounter, including:
- Pre-existing health conditions
- Pandemics
- Civil or political unrest
- Pregnancy and childbirth
- Certain risky activities
These are examples, not universal exclusions.
A different policy may cover, waive, or define some of these situations differently.
Common Travel Insurance Exclusions
1. Pre-Existing Medical Conditions
A pre-existing medical condition may be excluded under some policies.
However, certain plans offer a pre-existing condition exclusion waiver when specified requirements are satisfied.
Those requirements can include purchasing the policy within a defined period after the first trip payment and meeting other eligibility conditions.
Never assume a medical condition is automatically covered or automatically excluded.
Read the plan’s exact definition.
2. Foreseeable Events
Travel insurance is generally intended for unexpected events.
Buying insurance after a known problem has already developed may not create coverage for that problem.
For example, purchasing insurance after a named hurricane is already threatening your destination may be too late for hurricane-related cancellation protection.
Insurers can treat events that were already known or reasonably foreseeable differently from events that occur unexpectedly after purchase.
3. High-Risk Activities
Some policies exclude injuries related to certain adventure or extreme sports.
Examples can include:
- Skydiving
- Bungee jumping
- Backcountry skiing
- Mountaineering
- Certain racing activities
The NAIC specifically notes that risky activities such as bungee jumping, backcountry skiing, and snowboarding can appear among policy exclusions.
Adventure travelers should look for a policy that specifically covers the activities planned.
4. Alcohol or Drug-Related Incidents
Some insurance policies contain exclusions relating to losses associated with alcohol or drug use.
Definitions and requirements differ.
Read the exclusion wording rather than assuming that any alcohol consumption automatically voids the entire policy.
5. Changing Your Mind
Standard trip cancellation coverage generally does not reimburse you merely because you decide you no longer want to travel.
Examples might include:
- You become nervous about traveling.
- Your schedule changes.
- You decide the trip costs too much.
- Your preferred event is canceled.
- You simply no longer want to go.
CFAR-type protection may provide broader cancellation flexibility if its conditions are met.
6. Known Events
Travel insurance generally cannot be purchased after a known event with the expectation that it will cover that same event.
Timing matters.
This is one reason travelers often purchase insurance relatively soon after making significant nonrefundable trip payments.
7. Normal Pregnancy
Pregnancy-related coverage varies.
Routine pregnancy and childbirth may be excluded from some policies, while qualifying unforeseen medical complications may be treated differently.
NAIC lists pregnancy and childbirth among exclusions travelers can encounter.
Check the policy’s definitions carefully if pregnancy could affect your travel plans.
8. Civil or Political Unrest
Civil unrest and political events can be excluded by some policies.
Do not assume that a government advisory, demonstration, or political event automatically activates trip cancellation coverage.
The event must satisfy the policy terms.
Does Travel Insurance Cover Pandemics?
There is no universal answer.
Pandemic and epidemic coverage depends on the specific policy, the reason for the claim, and applicable exclusions or endorsements.
The NAIC includes pandemics among common exclusions that can appear in travel insurance.
Other policies may provide certain benefits for qualifying illness or other specifically defined circumstances.
Rather than asking only, “Does this policy cover pandemics?” ask:
Exactly which pandemic-related events are covered, and under which benefit?
That produces a much more useful answer.
Does Travel Insurance Cover Hurricanes?
Potentially—but timing and policy wording are critical.
A policy may cover specific hurricane-related circumstances such as:
- Destination becoming uninhabitable
- Qualifying travel disruption
- Other specifically listed covered events
But buying insurance after a storm has become a known or foreseeable event may prevent related coverage.
Do not wait until a major storm is already forecast and assume newly purchased insurance will protect the trip.
Does Travel Insurance Cover Terrorism?
Some policies include terrorism as a covered reason for cancellation or interruption under specific circumstances.
Others impose:
- Geographic requirements
- Timing rules
- Definitions of qualifying terrorist events
- Waiting periods
- Other restrictions
Fear of traveling after seeing disturbing news is not necessarily equivalent to a covered terrorism event.
Check the certificate or policy.
What Is Not a Travel Insurance Claim?
A disappointing trip is not automatically an insured loss.
Travel insurance generally is not designed to reimburse someone simply because:
- The weather was unpleasant.
- The hotel was disappointing.
- The beach was crowded.
- The traveler disliked the destination.
- Restaurant prices were higher than expected.
- A vacation did not meet expectations.
A financial loss generally needs to fall within a covered benefit and satisfy its terms.
Single-Trip vs. Annual Travel Insurance
Travelers can commonly choose between single-trip and multi-trip coverage.
Single-Trip Insurance
Designed around one specific journey.
It can make sense for:
- Occasional travelers
- Expensive vacations
- Cruises
- International trips
- Trips with significant prepaid expenses
Annual or Multi-Trip Insurance
Designed to cover qualifying trips during a policy year.
It can be useful for:
- Frequent travelers
- Business travelers
- People taking several vacations annually
But annual plans are not automatically more comprehensive.
They can impose:
- Maximum trip lengths
- Different cancellation limits
- Medical limits
- Per-trip restrictions
Compare benefits rather than simply comparing annual premiums.
Travel Insurance vs. Credit Card Travel Insurance
Some credit cards include travel protections, but card benefits should not automatically be treated as a complete substitute for standalone travel insurance.
Depending on the card, protections may include:
- Trip cancellation
- Trip interruption
- Travel delay
- Baggage delay
- Lost luggage
- Rental car damage coverage
- Emergency assistance
However, eligibility can depend on paying for some or all of the trip with the qualifying card.
Limits and covered reasons also vary.
A card might provide strong trip-delay protection but little or no emergency medical insurance.
Before purchasing separate insurance, check your card’s current Guide to Benefits and compare it with the trip’s actual risks.
Travel Insurance vs. Airline Trip Protection
Airlines, booking websites, cruise companies, and online travel agencies may offer insurance or trip-protection products during checkout.
Do not judge the product solely by convenience.
Before selecting the box, check:
- Who provides the insurance?
- What benefits are included?
- What cancellation reasons qualify?
- Does it include emergency medical coverage?
- Is evacuation covered?
- What are the limits?
- Are all parts of the trip covered?
- What exclusions apply?
A plan attached to an airline booking may not necessarily protect every hotel, tour, or other prepaid cost on the itinerary.
How Much Does Travel Insurance Cost?
Travel insurance prices vary according to the traveler, trip, coverage, and policy.
Pricing factors can include:
- Trip cost
- Traveler age
- Number of travelers
- Coverage level
- Policy type
- Optional upgrades
Allianz, for example, states that its travel insurance pricing generally considers traveler age, trip cost, and desired coverage level.
Avoid choosing a plan simply because it has the lowest premium.
A cheaper policy with insufficient medical or cancellation limits may provide poor protection for an expensive trip.
When Should You Buy Travel Insurance?
Travel insurance can often be purchased after the first trip payment, but buying earlier can matter because certain optional benefits or waivers have time-sensitive eligibility requirements.
These can include:
- Pre-existing condition waivers
- CFAR coverage
- Certain supplier-default benefits
The exact purchase window differs by policy.
This makes the first trip deposit date important.
If you wait until shortly before departure, some options may no longer be available.
How Do You Choose a Travel Insurance Policy?
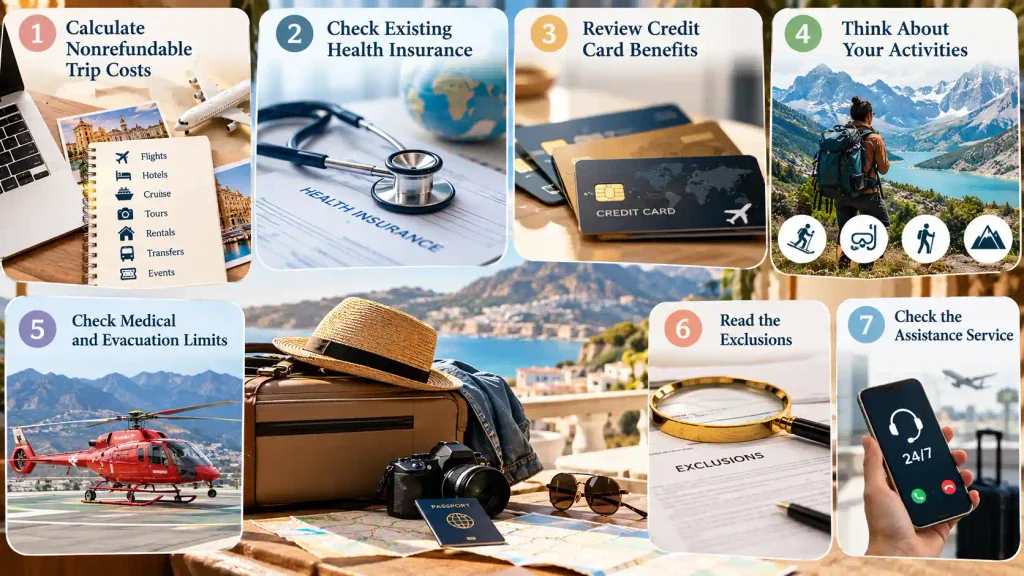
Do not begin by asking which company has the cheapest plan.
Start with your actual financial risks.
1. Calculate Nonrefundable Trip Costs
Add up prepaid expenses you would lose if the trip were canceled.
These could include:
- Airfare
- Hotels
- Cruise fare
- Tours
- Vacation rentals
- Transfers
- Event bookings
Refundable reservations do not create the same insurance need as nonrefundable expenses.
2. Check Existing Health Insurance
Find out whether your regular health plan provides coverage at your destination.
For international travel, ask specifically about:
- Emergency treatment
- Out-of-network care
- Overseas hospitals
- Medical evacuation
- Reimbursement procedures
The State Department recommends checking these details before traveling abroad.
3. Review Credit Card Benefits
Determine what protection already comes with the card used to pay for the trip.
Avoid paying twice for coverage you already have unless the standalone policy meaningfully improves it.
4. Think About Your Activities
A beach vacation and a mountaineering trip do not present identical risks.
Confirm coverage if you plan:
- Skiing
- Scuba diving
- Trekking
- Mountain climbing
- Adventure sports
- Remote-area travel
5. Check Medical and Evacuation Limits
This becomes particularly important abroad.
A policy with excellent cancellation protection but very low medical coverage may not match the needs of an international traveler.
6. Read the Exclusions
This is where many misunderstandings begin.
Do not read only the marketing summary.
Review the certificate, policy, or description of coverage.
7. Check the Assistance Service
The State Department recommends finding out whether the insurer provides a 24-hour help line.
Emergency assistance can help travelers navigate:
- Medical facilities
- Evacuations
- Lost documents
- Travel disruptions
- Other covered emergencies
How Do Travel Insurance Claims Work?
Travel insurance usually reimburses eligible losses after the traveler submits a claim and supporting documentation, although procedures differ by insurer and benefit.
A typical process includes:
- Notify the relevant travel supplier.
- Reduce further financial loss where reasonably possible.
- Contact the insurer or assistance provider.
- Gather documentation.
- Submit the claim.
- Respond to requests for additional evidence.
- Wait for the insurer’s decision.
The documentation needed depends on the claim.
What Documents Might You Need for a Claim?
Keep records throughout the trip.
Depending on the claim, useful documents can include:
- Travel itinerary
- Booking confirmations
- Proof of payment
- Cancellation notices
- Receipts
- Medical documentation
- Physician statements
- Police reports
- Airline delay confirmations
- Baggage reports
- Refund statements
- Credit card statements
For example, a baggage-delay claim may require documentation showing when the bag was delayed plus receipts for qualifying essential purchases.
A cancellation claim based on illness may require medical evidence.
Do not throw receipts away simply because the expense seems minor.
What Should You Do When Something Goes Wrong During a Trip?
If a potentially covered problem occurs:
First, deal with the immediate emergency.
Then, as soon as practical:
- Contact the insurer.
- Contact the airline, hotel, or other supplier.
- Ask what documentation is required.
- Save receipts.
- Take photographs when relevant.
- Request written reports.
- Record names, dates, and reference numbers.
For serious medical emergencies, use the insurer’s emergency assistance line when circumstances allow.
Medical evacuation in particular should generally be coordinated with the insurer or assistance provider rather than independently arranged unless an immediate emergency makes that impossible.
Is Travel Insurance Worth It?
Travel insurance can be particularly useful when a trip involves substantial nonrefundable expenses, limited medical coverage at the destination, international travel, remote locations, or financial losses the traveler would struggle to absorb.
Its usefulness depends on the trip.
Consider a $300 domestic weekend where the hotel and flight are fully refundable.
The financial exposure may be relatively small.
Now compare that with a $12,000 international cruise containing:
- Nonrefundable airfare
- Prepaid cruise fare
- Excursions
- Hotels
- Limited overseas medical coverage
The potential financial loss is very different.
Insurance decisions should therefore be based on the risks you need transferred—not simply on the destination.
Common Travel Insurance Mistakes To Avoid
Many coverage problems begin before the trip.
Common mistakes include:
- Buying solely on price
- Not reading exclusions
- Assuming every cancellation reason is covered
- Waiting too long to purchase time-sensitive benefits
- Forgetting to insure important prepaid costs
- Assuming domestic health insurance works overseas
- Ignoring adventure-sport exclusions
- Confusing travel assistance with insurance
- Not keeping receipts
- Failing to document delays or baggage problems
- Assuming credit card coverage is comprehensive
- Arranging expensive medical evacuation without checking policy procedures when circumstances allow
The best time to understand a policy is before a claim occurs.
Final Thoughts
Travel insurance works best when you understand exactly what financial risks you are transferring to the insurer.
For a simple, inexpensive trip with refundable bookings, extensive coverage may be less important. For an expensive international vacation, cruise, remote journey, or itinerary with substantial nonrefundable costs, cancellation, medical, and evacuation protection can become much more significant.
Before buying, compare your existing health insurance and credit card benefits with the policy you are considering. Then read the covered reasons, exclusions, limits, deductibles, purchase deadlines, and claim procedures not just the marketing summary.
Most importantly, remember that travel insurance is policy-specific. If a particular risk matters to your trip, confirm in the actual policy documents that it is covered before relying on it.
Frequently Asked Questions
No. Travel insurance covers specified risks subject to policy terms, benefit limits, conditions, and exclusions.
It can, depending on why the flight was canceled, what financial loss occurred, and which benefit applies. Trip cancellation does not mean every airline cancellation automatically produces an insurance payout.
Usually not. Standard trip cancellation generally requires a covered reason. CFAR-type coverage can provide broader flexibility but usually costs extra and reimburses only part of eligible expenses.
It depends on the policy. Some exclude qualifying pre-existing conditions, while others may offer an exclusion waiver when specified requirements are met.
Medicare generally does not cover healthcare outside the U.S., although limited exceptions exist. Travelers should check their specific coverage before leaving the country. The State Department recommends considering supplemental travel medical insurance when existing coverage is insufficient.
Many comprehensive plans include it, while other travelers purchase separate medical evacuation coverage. Limits, eligibility, destinations, and transportation rules vary.
Many plans include baggage-loss benefits, but reimbursement limits, item limits, exclusions, and documentation requirements apply.
Standard trip cancellation generally will not cover a simple change of mind. Qualifying CFAR coverage may provide partial reimbursement when its requirements are satisfied.
Possibly. Compare the card’s benefits with the risks of your specific trip. Credit card coverage may leave gaps in areas such as emergency medical expenses or evacuation.
Often, yes. However, some benefits and waivers have purchase deadlines linked to your initial trip deposit, so delaying can reduce the options available.
Not always. Certain policies exclude high-risk activities, while specialized plans may cover them. Verify the exact activity before purchasing.
It depends on your financial exposure. A costly domestic vacation with substantial nonrefundable reservations may justify insurance even though international medical coverage is not a concern.