Looking for the Best Travel Credit Card? Unlock Premium Travel Rewards
The best travel credit cards in 2026 include Chase Sapphire Preferred for flexible travel rewards, Capital One Venture X for premium benefits at a comparatively moderate annual fee, and American Express Platinum for frequent travelers who value airport lounge access and luxury travel privileges. However, the right card depends on how often you travel, where you spend money, which airlines you use, and whether the rewards outweigh the annual fee.
A credit card can make a meaningful difference to the cost of a trip. Everyday purchases can generate points toward flights, hotel reservations, or upgrades, while certain cards provide airport lounge access, travel credits, and insurance benefits. Yet a card with impressive advertised perks is not necessarily the most rewarding option for everyone.
For example, someone taking two international trips a year may benefit more from a $95 card with flexible rewards than from an $895 premium card whose benefits require frequent use.
This guide compares leading U.S. travel credit cards in 2026, explains how their rewards work, and shows how to choose a card that provides practical value rather than simply a long list of benefits.
Scope: This guide covers U.S.-issued consumer travel credit cards. Card availability, eligibility, fees, rewards, and promotional offers differ by country. Product details were checked against issuer information available in October 2026.
Explore This Guide: United TravelBank: How to Use Travel Credits in 2026
What Are the Best Travel Credit Cards in 2026?
The strongest travel credit cards serve different spending habits. Some reward a broad range of purchases, while others concentrate their value in airline bookings, hotel stays, or premium travel privileges.
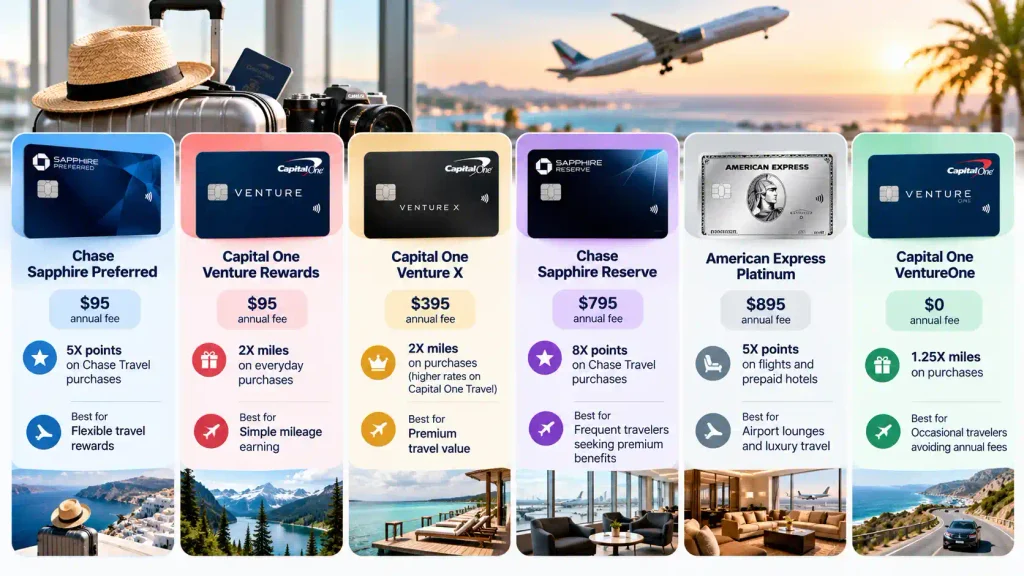
Here is a comparison of six notable options.
| Travel credit card | Annual fee | Key earning feature | Best suited for |
| Chase Sapphire Preferred | $95 | 5X points on eligible Chase Travel purchases | Flexible travel rewards |
| Capital One Venture Rewards | $95 | 2X miles on everyday purchases | Simple mileage earning |
| Capital One Venture X | $395 | 2X miles on purchases; higher rates through Capital One Travel | Premium travel value |
| Chase Sapphire Reserve | $795 | 8X points on Chase Travel purchases | Frequent travelers seeking premium benefits |
| American Express Platinum | $895 | 5X points on eligible flights and prepaid hotels | Airport lounges and luxury travel |
| Capital One VentureOne | $0 | 1.25X miles on purchases | Occasional travelers avoiding annual fees |
Fees and selected earning rates are based on issuer-published information. Bonus-category caps, eligible purchases, exclusions, and enrollment requirements apply.
The annual fee is only one part of the comparison. A card with a higher fee may be worthwhile when its benefits replace expenses the traveler would otherwise pay. Conversely, a no-fee card may deliver better net value for someone who travels infrequently.
What Makes a Travel Credit Card Worth Having?
A travel credit card earns rewards that can be used for travel-related expenses, such as airfare, hotels, and sometimes car rentals. Depending on the issuer, rewards may take the form of transferable points, fixed-value miles, airline miles, or hotel loyalty points.
The most useful cards generally combine three elements: rewards on purchases you already make, redemption options that match your travel habits, and benefits that reduce actual travel expenses.
How Are Travel Rewards Different From Regular Cash Back?
Cash-back cards usually return a percentage of eligible spending as money or statement credits.
Travel cards may offer several redemption methods, including transfers to participating airline and hotel loyalty programs.
For example, a traveler might transfer flexible credit card points to an airline program and use them toward an award ticket. The value depends on the airline’s award pricing, taxes, fees, and seat availability.
This flexibility can be valuable, but it also requires more attention than simply redeeming cash back.
Which Features Should You Compare First?
| Feature | Why it matters |
| Annual fee | Determines the recurring cost of keeping the card |
| Rewards rate | Controls how quickly eligible purchases earn points |
| Transfer partners | Provides additional flight and hotel redemption options |
| Airport lounge access | Can improve airport comfort on frequent trips |
| Travel credits | May offset eligible travel expenses |
| Foreign transaction fees | Affect the cost of international purchases |
| Travel insurance | Can provide protection for qualifying disruptions |
| Redemption restrictions | Determine how easily rewards can be used |
A particularly important distinction is whether a benefit applies automatically or requires booking through the issuer’s travel portal.
A hotel credit restricted to one booking platform is not equivalent to unrestricted money toward any hotel.
Is Chase Sapphire Preferred the Best Overall Travel Credit Card?
Chase Sapphire Preferred is one of the strongest choices for travelers who want transferable points and useful travel protections without paying a premium annual fee.
Annual fee: $95
The card earns 5X points on eligible Chase Travel purchases, 3X on dining and several everyday categories, and 2X on other eligible travel purchases.
In June 2026, Chase expanded the card’s earning categories to include 3X points on gas and EV charging, along with qualifying vacation-home purchases. The annual fee remained $95.
media.chase.com+1
Why Is Chase Sapphire Preferred Useful for Travelers?
Its appeal comes from the combination of flexible rewards and practical travel benefits.
Travelers can earn points through everyday spending and use eligible rewards through Chase’s redemption options or participating transfer partners.
The card also provides travel protections, subject to the relevant benefit terms, including trip cancellation and interruption insurance, trip delay coverage, and rental car protection.
These benefits can matter when a trip does not go as planned.
Who Should Consider Chase Sapphire Preferred?
It is particularly suitable for travelers who:
- Want a relatively low annual fee.
- Spend regularly on dining and travel.
- Prefer flexible rewards over one airline’s miles.
- Value travel insurance and transfer partners.
A traveler who takes several trips each year but rarely uses airport lounges may find this card more practical than a premium alternative.
Is Capital One Venture X the Best Premium Travel Card for Its Annual Fee?
Capital One Venture X combines straightforward everyday mileage earning with airport lounge access and annual travel benefits.
Annual fee: $395
Cardholders earn 2X miles on purchases, 5X miles on eligible flights and vacation rentals booked through Capital One Travel, and 10X miles on eligible hotels and rental cars booked through the same platform.
The card also provides a $300 annual Capital One Travel credit and 10,000 anniversary miles beginning on the first anniversary.
Can the Venture X Travel Credit Offset Its Annual Fee?
It can substantially reduce the effective cost for someone who would naturally use Capital One Travel.
- Consider this illustrative calculation:
- Venture X Annual Value Example
- Annual fee: $395
- Annual travel credit used: −$300
- 10,000 anniversary miles at 1 cent each: −$100
- Illustrative net −$5
This assumes full use of the travel credit and a $100 redemption value for anniversary miles. It is not a cash refund or guaranteed saving. Redemption terms and first-year timing matter.
The calculation demonstrates the card’s potential value, but only when the benefits match actual spending.
A traveler who avoids booking through Capital One Travel should not automatically count the entire $300 credit as savings.
Does Venture X Include Airport Lounge Access?
Yes. Eligible primary cardholders receive access to Capital One Lounge and Landing locations and participating Priority Pass lounges, subject to current access rules and enrollment requirements.
Capital One advertises access to more than 1,300 participating Priority Pass lounges worldwide.
Lounge availability varies by airport, and guest access rules may differ from primary cardholder privileges.
Check This Out: LaGuardia Airport Lounges: Complete LGA Traveler Guide 2026
Is American Express Platinum Worth Its $895 Annual Fee?
American Express Platinum is designed for travelers who can use premium airport, hotel, and lifestyle benefits regularly.
Annual fee: $895
The card earns 5X Membership Rewards points on eligible flights purchased directly from airlines or through American Express Travel, subject to a $500,000 annual purchase cap. It also earns 5X on eligible prepaid hotels booked through AmexTravel.com.
American Express confirms the $895 annual fee in its July 2026 product guidance.
What Makes American Express Platinum Different?
Its strongest appeal is the collection of premium travel and lifestyle privileges rather than its everyday rewards rate.
Eligible cardholders can access the American Express Global Lounge Collection, including Centurion Lounges, participating Priority Pass locations, and other qualifying lounges.
Some partner lounges impose visit limits, enrollment conditions, or specific travel requirements.
The card also provides hotel-related benefits and numerous statement credits, each governed by its own terms.
When Does the Platinum Card Make Financial Sense?
It may be worthwhile for travelers who frequently purchase flights, use participating airport lounges, stay at eligible hotels, and can naturally use the included credits.
For example, a frequent business traveler who regularly visits airports with participating lounges may derive meaningful value from lounge access alone.
Someone taking one short holiday annually may struggle to justify the fee.
The key is to value benefits according to actual use, not the maximum advertised value of the benefits package.
Is Chase Sapphire Reserve Better Than Sapphire Preferred?
Chase Sapphire Reserve offers a broader premium travel package, but its higher annual fee means it is better suited to frequent travelers who will actively use the benefits.
Annual fee: $795
The Reserve earns 8X points on eligible Chase Travel purchases, 4X on flights and hotels booked directly, and 3X on dining. It also includes a $300 annual travel credit and eligible airport lounge access.
How Do the Two Chase Sapphire Cards Compare?
| Feature | Sapphire Preferred | Sapphire Reserve |
| Annual fee | $95 | $795 |
| Chase Travel purchases | 5X | 8X |
| Other travel | 2X | 4X on direct airline and hotel bookings |
| Dining | 3X | 3X |
| Annual travel credits | Selected credits with conditions | $300 general travel credit, plus selected credits |
| Airport lounge access | Not a standard benefit | Eligible lounge access |
| Ideal traveler | Occasional to regular | Frequent and premium |
Reserve’s $300 travel credit is especially flexible because qualifying purchases do not have to be made through Chase Travel. Chase states that eligible expenses can include flights, hotels, taxis, and other travel purchases.
However, even after fully using that credit, the $795 annual fee leaves a substantial cost to justify through other benefits.
For many travelers, Sapphire Preferred provides a more economical entry into flexible travel rewards.
Is Capital One Venture Rewards the Best Card for Simple Travel Miles?
Capital One Venture Rewards is a practical choice for travelers who prefer earning the same base rate on most purchases instead of tracking numerous bonus categories.
- Annual fee: $95
- Everyday rewards: 2X miles
Capital One confirms that the card earns 2X miles on everyday purchases and carries a $95 annual fee.
Why Might Flat-Rate Miles Be More Useful Than Bonus Categories?
A traveler who spends across many categories may earn rewards more consistently with a flat-rate card.
For example, $20,000 in eligible annual spending at 2X miles per dollar would generate 40,000 miles.
The actual redemption value depends on how those miles are used.
The card is particularly appealing to people who want travel rewards without carefully managing spending categories every month.
Which Travel Credit Card Is Best Without an Annual Fee?
Capital One VentureOne is a useful option for travelers who want mileage rewards without committing to an annual fee.
The card has a $0 annual fee and earns 1.25X miles on everyday purchases, according to Capital One’s published comparison.
A no-fee card can make sense when the traveler does not spend enough to justify a paid card or does not expect to use premium benefits.
Is a No-Fee Travel Card Better for Occasional Travelers?
Often, yes.
Someone who travels once a year may prefer to accumulate rewards gradually rather than pay for airport lounge access or annual credits that go unused.
However, no-fee cards can have lower earning rates and fewer protections.
The right comparison is the value of the rewards and benefits you will actually receive after subtracting all card costs.
Is American Express Gold a Better Choice for Food Spending and Travel Rewards?
American Express Gold is worth considering for travelers whose largest everyday expenses include restaurants and groceries.
The card carries a $325 annual fee and earns 4X points at restaurants worldwide on up to $50,000 in purchases per calendar year, and 4X at U.S. supermarkets on up to $25,000 annually.
It also earns 5X on eligible prepaid hotels booked through AmexTravel.com and 3X on eligible flights.
Can Everyday Grocery Spending Help Pay for Flights?
Yes. Credit card points earned through eligible everyday purchases can later be redeemed toward travel through supported redemption options.
Suppose a household spends $8,000 annually at eligible U.S. supermarkets.
At 4X points per dollar, that spending generates 32,000 Membership Rewards points.
Those points do not have one guaranteed cash value. Their usefulness depends on the redemption method and available airline or hotel partners.
The Gold card is especially relevant when dining and grocery spending are significant, but its statement credits should be valued only if they fit existing habits.
Are Airline Credit Cards Better Than General Travel Rewards Cards?
Airline-branded credit cards can be more valuable when a traveler frequently uses the same airline and benefits from its specific privileges.
General travel rewards cards, however, offer greater flexibility for people who compare multiple airlines before booking.
What Is the Difference Between the Two?
| Feature | General travel rewards card | Airline-branded card |
| Rewards | Flexible bank points or miles | Usually a specific airline’s miles |
| Flight redemption | Multiple possible programs | Primarily airline loyalty program and partners |
| Checked baggage benefits | Varies | May include airline-specific allowances |
| Priority boarding | Not typical | Often available on eligible cards |
| Airport lounge access | Selected premium cards | Selected premium airline cards |
| Best suited for | Travelers using different airlines | Loyal customers of one airline |
For example, someone regularly flying with airlines listed in the AirlineLocations directory may prefer flexible bank points when their bookings vary by route, price, and availability.
A traveler loyal to one airline may instead prioritize a card that provides qualifying checked baggage benefits or priority boarding.
These benefits must be verified for the specific card and fare. Holding an airline-branded credit card does not automatically provide free baggage on every flight.
How Can You Calculate the Real Value of a Travel Credit Card?
The most reliable approach is to compare the rewards and benefits you will actually use against the annual fee and other costs.
A card’s advertised benefit value can be misleading when it includes credits restricted to merchants or services you rarely purchase.
What Is the Simplest Way to Calculate Annual Card Value?
Netannualvalue=Rewardsvalue+Benefitsused-Annualfee-Othercosts
Consider two hypothetical cards:
| Annual factor | Card A | Card B |
| Rewards redeemed | $180 | $300 |
| Travel benefits used | $40 | $250 |
| Annual fee | $95 | $395 |
| Net annual value | $125 | $155 |
Card B provides slightly greater value in this example, but only because its owner uses the travel benefits.
If those benefits go unused, Card A becomes the stronger option.
How Much Are Travel Points Worth?
There is no universal value for a travel reward point.
Some points can be redeemed at a predictable rate toward eligible travel purchases, while airline transfers may produce higher or lower values depending on the booking.
For example, if an award flight requires 30,000 points and the equivalent cash fare is $450, with $50 in additional award taxes and fees:
\[ \frac{\$450-\$50}{30,000}\times100 =1.33\text{ cents per point} \]
This is an illustrative redemption value, not a guaranteed rate.
The calculation should compare equivalent fares and account for taxes, fees, and any benefits forfeited by booking an award ticket.
How Can You Get the Most Value From Travel Credit Card Points?
Travel rewards become more useful when travelers understand both how points are earned and how they are redeemed.
Should You Transfer Points to Airline Loyalty Programs?
Transfers can be worthwhile when the airline program offers an attractive award redemption.
However, transfers are often irreversible, and award availability can change.
Before transferring points, confirm the required number of miles, applicable taxes and fees, and whether the desired seat is available.
For example, transferring points for a business-class award may provide attractive value when the equivalent cash ticket is expensive. But transferring without checking availability can leave points stranded in a program.
Is Booking Through a Credit Card Travel Portal Always Better?
No.
Travel portals may provide higher earning rates or access to particular credits, but travelers should compare the total booking price and conditions against booking directly.
Consider the following before selecting a booking channel:
- Total fare or room price.
- Cancellation and modification rules.
- Airline loyalty mileage eligibility.
- Hotel loyalty benefits.
- Availability of travel credits.
- Customer support responsibility when plans change.
A portal booking that earns extra points may be less attractive if the same reservation costs more or carries less flexible conditions.
Should You Use Points for Economy or Business Class?
Neither is automatically the better redemption.
Business-class awards sometimes provide high cents-per-point values, but the relevant question is whether the redemption saves money on travel you genuinely want.
A traveler who would otherwise purchase an economy ticket may prefer several economy redemptions over one premium-cabin journey.
The best redemption is the one that delivers meaningful value for your own travel plans.
What Travel Credit Card Benefits Matter Most for International Trips?
For international travelers, avoiding unnecessary fees and gaining access to useful travel protections can be just as important as earning rewards.
Why Do Foreign Transaction Fees Matter?
Some credit cards charge a foreign transaction fee when purchases are processed internationally.
For example, a 3% foreign transaction fee on $3,000 in eligible overseas spending would cost $90.
Travelers who regularly pay for hotels, restaurants, or transportation abroad should compare the foreign transaction fee listed in each card’s current pricing terms.
A card with no foreign transaction fees can be particularly useful when traveling across several countries.
Do Travel Credit Cards Include Insurance?
Selected travel credit cards provide protections such as trip cancellation insurance, trip interruption coverage, baggage delay coverage, rental car protection, or emergency assistance.
However, these benefits have conditions.
A trip cancellation policy may cover specified unexpected events but not a passenger’s voluntary decision to abandon a trip.
For example, a qualifying illness might be covered under a card’s insurance terms, while canceling because the destination is no longer appealing may not be.
Always review the card’s Guide to Benefits, coverage limits, exclusions, and claim requirements.
Can Credit Cards Help With Airport Lounge Access?
Yes. Premium cards such as Chase Sapphire Reserve, Capital One Venture X, and American Express Platinum offer access to qualifying lounge networks.
But lounge membership does not guarantee entry at every airport.
Travelers should check terminal location, participating lounges, operating hours, capacity restrictions, guest fees, and any required enrollment.
Are Travel Credit Card Welcome Bonuses Worth Pursuing?
A welcome bonus can provide substantial rewards when a new cardholder meets the required spending conditions.
However, offers change frequently and may vary by applicant or application channel.
The most important consideration is whether the required purchases fit your normal budget.
For example, if a card requires $5,000 in eligible purchases within three months, the spending target averages approximately $1,667 per month.
Someone who already spends that amount may find the requirement manageable. Someone who must make unnecessary purchases to qualify should reconsider.
Welcome bonuses should be evaluated alongside annual fees, eligibility restrictions, and the possibility of interest charges.
Can Credit Card Interest Cancel Out Your Travel Rewards?
Yes. Interest charges can quickly outweigh the value of travel points.
The Consumer Financial Protection Bureau explains that cardholders can generally avoid interest on new purchases when their card provides a grace period and they pay the statement balance in full by the due date.
Consumer Financial Protection Bureau
Consider a simplified example: earning $200 worth of travel rewards is not beneficial if carrying the resulting debt produces $300 in interest charges.
A travel credit card works best as a payment and rewards tool, not as a reason to borrow more than you can comfortably repay.
Which Travel Credit Card Matches Your Travel Style?
Choose your main priority
- Flexible points and a moderate annual fee
- Simple rewards on everyday spending
- Airport lounges and travel credits
- Luxury travel and extensive premium benefits
- No annual fee
Chase Sapphire Preferred
A $95 annual fee, flexible points and travel protections make it a useful starting point.This is a general comparison based on travel preferences, not a credit approval or individualized financial recommendation.
Related: 60+ Best Credit Card Referral Bonuses to Know in 2026
Conclusion: Which Travel Credit Card Should You Choose?
The best travel credit card is not necessarily the one with the highest annual fee or the largest advertised rewards package. It is the card that rewards your regular spending and provides benefits you will genuinely use.
Chase Sapphire Preferred offers a strong balance of flexible rewards and manageable cost, while Capital One Venture X provides an appealing combination of premium benefits and everyday mileage earning. American Express Platinum is better suited to travelers who regularly use airport lounges and luxury travel privileges. For occasional travelers, a no-annual-fee option may be more sensible.
Before applying, compare current issuer terms, annual fees, redemption options, foreign transaction fees, and travel protections. Most importantly, consider whether you can pay your balance in full each month. The real benefit of travel rewards comes from reducing travel costs, not creating additional debt to earn points.
Related FAQs!
Chase Sapphire Preferred can be a useful starting point for people comfortable with a $95 annual fee and interested in transferable points. Travelers who prefer to avoid annual fees may find Capital One VentureOne more suitable.
American Express Platinum, Chase Sapphire Reserve, and Capital One Venture X are prominent options. The best choice depends on the lounges available at the airports you actually use and each card’s access restrictions.
Yes. Eligible points can be redeemed through travel portals or transferred to participating airline loyalty programs. The number of points required depends on the redemption method, route, cabin, and availability.
Expiration rules vary by rewards program. Some bank points remain available while an account is open and in good standing, while airline or hotel points may follow different inactivity or expiration policies.
Students should generally prioritize manageable fees, eligibility requirements, and responsible credit use. A student or no-annual-fee credit card may be more appropriate than a premium travel card, particularly for someone building credit history.
Yes, subject to issuer approval and account eligibility. Multiple cards may complement one another, but additional annual fees and account management can reduce their overall value.
It depends on the redemption value. Compare the cash price, points required, taxes, fees, and booking conditions before deciding.
Some airline-branded cards offer qualifying baggage benefits, often subject to booking and loyalty-account conditions. General travel rewards cards do not automatically provide free checked baggage on every airline.
A formal credit card application may result in a hard credit inquiry, which can affect a credit score. Some issuers provide eligibility checks that do not initially affect the score. Review the issuer’s application disclosures.
Usually only when the traveler can obtain enough value from rewards and benefits to justify the fee. Someone taking one vacation annually may be better served by a lower-fee or no-fee card.