Why the Chase Sapphire Preferred Is Worth Keeping
The Chase Sapphire Preferred® Card can be worth keeping for years because of its transferable Ultimate Rewards points, travel protections, bonus earning categories, and annual hotel credit. Although the card carries a $95 annual fee, its combination of travel benefits and rewards flexibility can provide lasting value for eligible cardholders.
Many travel credit cards offer attractive introductory bonuses, but their long-term usefulness depends on what happens after the first year. A card that keeps rewarding everyday spending, offers useful protections, and supports multiple redemption options may remain valuable even after the welcome offer expires.
The Chase Sapphire Preferred sits between basic rewards cards and premium travel cards with much higher annual fees. It gives cardholders access to Chase’s airline and hotel transfer partners without requiring them to maintain an expensive luxury travel card.
However, keeping the card is not automatically the best decision for every account holder. Annual spending, travel habits, reward redemption preferences, and the ability to use available credits all influence its value.
This guide covers the main reasons to keep the Chase Sapphire Preferred Card, how its benefits work, when the annual fee may be justified, and when closing or downgrading the account may make more sense.
Card benefits, fees, and promotional offers can change. The analysis below distinguishes established card features from terms you should confirm in Chase’s current cardmember agreement.
Related: Chase Sapphire Reserve vs Amex Platinum: 2026 Guide
Chase Sapphire Preferred Card at a Glance
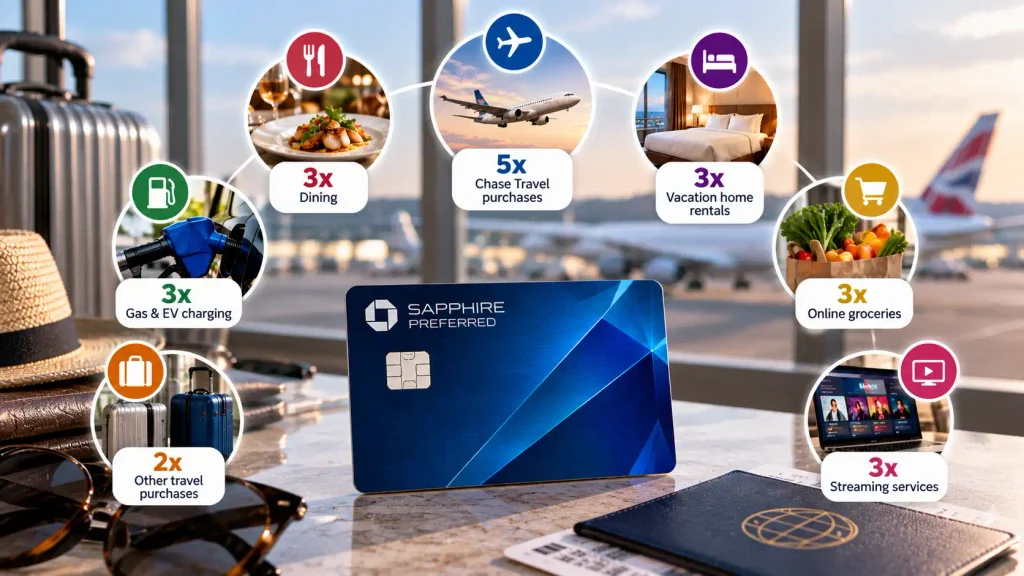
The Chase Sapphire Preferred is a travel rewards credit card that earns Chase Ultimate Rewards points on eligible purchases. Its rewards structure covers travel, dining, groceries, gas, and selected everyday expenses.
The card also provides travel insurance benefits and access to airline and hotel loyalty programs.
| Feature | Chase Sapphire Preferred Details |
| Annual fee | $95 |
| Rewards currency | Chase Ultimate Rewards points |
| Chase Travel purchases | 5x points |
| Dining | 3x points |
| Gas and EV charging | 3x points |
| Eligible vacation home rentals | 3x points |
| Select streaming services | 3x points |
| Eligible online groceries | 3x points |
| Other travel purchases | 2x points |
| Other eligible purchases | 1x points |
| Annual Chase Travel hotel credit | Up to $100 |
| Global Entry, TSA PreCheck, or NEXUS | Up to $120 every four years |
| Foreign transaction fees | None |
| Complimentary airport lounge access | Not included |
These benefits reflect Chase’s June 2026 card enhancements, which introduced additional rewards categories and increased the annual hotel credit without changing the $95 fee.
1. Primary Rental Car Coverage Is a Valuable Long-Term Benefit
One of the strongest reasons to keep the Chase Sapphire Preferred is its primary auto rental collision damage coverage.
Rental car companies often offer optional collision damage waivers that increase a reservation’s total cost. Although these waivers can provide useful protection, eligible cardholders may already have comparable coverage through their credit card for certain losses.
How Does Primary Rental Car Insurance Work?
Primary rental car coverage lets eligible cardholders submit covered claims directly to the card’s benefits administrator without first filing with their personal auto insurer.
This differs from secondary coverage, which may require the cardholder to file a claim with their personal insurance before receiving reimbursement.
The Chase Sapphire Preferred provides primary coverage for eligible rental vehicles when the cardholder meets the applicable conditions.
Chase’s current benefits include reimbursement of up to $60,000 for theft and collision damage to most eligible rental vehicles with a manufacturer’s suggested retail price of $125,000 or less.
Requirements for Rental Car Coverage
To qualify, the cardholder generally must:
- Pay for the entire eligible rental transaction with the Chase Sapphire Preferred Card or qualifying rewards.
- Decline the rental company’s collision damage waiver or loss damage waiver.
- Be an authorized driver under the rental agreement.
- Follow the coverage terms and claim procedures.
Coverage exclusions apply to certain vehicle categories, rental periods, countries, and circumstances.
Importantly, collision coverage is not the same as comprehensive automobile insurance. It generally does not replace liability insurance for injuries or damage to another person’s property.
How Can This Benefit Save Money?
Consider an eligible rental car reservation lasting seven days.
If the rental company charges $25 per day for an optional collision damage waiver, declining that waiver could save $175 in rental charges.
That potential saving exceeds the card’s $95 annual fee.
However, the example assumes the card’s coverage applies to the rental and that the traveler does not need additional protection.
The financial benefit depends on rental frequency, insurance arrangements, and each reservation’s terms.
2. Travel Insurance Adds Protection Beyond Rental Cars
Travel disruptions can generate unexpected expenses, particularly when flights are delayed, luggage arrives late, or prepaid arrangements cannot be used.
The Chase Sapphire Preferred includes several travel protection benefits that may reimburse eligible losses.
These protections are especially relevant for travelers booking multiple flights, hotel reservations, or other prepaid travel services.
Trip Cancellation and Interruption Insurance
The card provides coverage for certain nonrefundable travel expenses when a trip is canceled or interrupted for a covered reason.
Eligible circumstances may include illness, severe weather, or other events specified in the benefits guide.
Current coverage limits include up to $10,000 per covered traveler and $20,000 per trip.
For example, a traveler who must cancel a prepaid trip because of a qualifying medical emergency may be eligible for reimbursement of covered, nonrefundable expenses.
However, voluntary cancellations and ordinary changes of travel plans are not automatically covered.
Trip Delay Reimbursement
Flight delays can result in unexpected hotel, meal, and transportation expenses.
The Chase Sapphire Preferred provides trip delay reimbursement when an eligible common-carrier journey is delayed more than 12 hours or requires an overnight stay.
The benefit provides up to $500 per covered traveler for eligible unreimbursed expenses.
For example, an overnight flight disruption that requires an additional hotel stay may qualify, provided the delay meets the policy requirements.
Receipts and documentation from the transportation provider may be required.
Baggage Delay Insurance
The card also reimburses essential purchases when checked baggage is delayed for more than six hours.
Eligible expenses may include toiletries and clothing needed during the delay.
The coverage limit is up to $100 per day for a maximum of five days.
This benefit can be particularly useful when luggage is delayed at the beginning of an international trip.
Lost Luggage Reimbursement
If checked or carry-on baggage is lost, stolen, or damaged during a covered journey, the card may reimburse eligible losses.
The maximum benefit is $3,000 per covered traveler, subject to exclusions and limitations for certain belongings.
Airline compensation and other reimbursements can affect the amount payable.
Emergency Evacuation and Transportation
The card’s June 2026 enhancements added emergency evacuation and transportation coverage.
Under specified circumstances, eligible travelers who become ill or injured during a trip at least 100 miles from home may qualify for covered emergency transportation and medical services.
The maximum benefit is $100,000.
This is a specialized benefit rather than general travel medical insurance. Travelers should review its requirements carefully, particularly for international trips.
3. Chase Ultimate Rewards Transfer Partners Provide Flexibility
Access to Chase’s airline and hotel transfer partners is another major reason to retain the Sapphire Preferred.
You can redeem Ultimate Rewards points in several ways, but transfers to eligible loyalty programs let you book award flights and hotel stays.
This flexibility can be especially useful when award availability or cash prices change.
Airline Transfer Partners
- Air Canada Aeroplan
- Air France–KLM Flying Blue
- British Airways Club
- Singapore Airlines KrisFlyer
- Southwest Rapid Rewards
- Virgin Atlantic Flying Club
- JetBlue TrueBlue
- Aer Lingus AerClub
- Iberia Club
Chase supports transfers to several airline loyalty programs, including:
These programs offer access to different airline networks and award redemption options.
For example, Aeroplan points may be used for eligible flights operated by Air Canada and participating Star Alliance partners.
Similarly, British Airways Club members can redeem Avios for qualifying flights across its partner network.
Award prices, taxes, surcharges, and seat availability vary by program.
Hotel Transfer Partners
Chase also supports transfers to participating hotel loyalty programs, including World of Hyatt, Marriott Bonvoy, IHG One Rewards, and Wyndham Rewards.
A significant change took effect in 2026.
As of October 1, 2026, Chase Sapphire Preferred points will transfer to World of Hyatt at a 4:3 ratio, up from the previous 1:1 rate.
This means 4,000 Ultimate Rewards points now convert to 3,000 World of Hyatt points.
Most other listed transfer partners continue to support a 1:1 ratio, subject to current program terms.
Why Transfer Flexibility Matters
Suppose an eligible airline award flight requires 25,000 miles.
If the transfer ratio is 1:1, a cardholder can transfer 25,000 Ultimate Rewards points to the participating loyalty program.
However, complete the transfer only after confirming the award seat is available and the required taxes and fees are acceptable.
Transfers are generally irreversible.
Cardholders should also compare the award booking against the cash fare to determine whether transferring points offers reasonable value.
4. The Annual Hotel Credit Can Offset the Card’s Fee
The Chase Sapphire Preferred provides up to $100 in statement credits each account anniversary year for eligible hotel stays purchased through Chase Travel.
This benefit increased from $50 to $100 in June 2026. When fully used, thee credit can offset the $95 annual fed, making it a meaningful component of the card’s long-term value.
How Does Hotel Credit Work?
Cardholders must make an eligible prepaid hotel booking through Chase Travel using the Sapphire Preferred.
The credit is applied as a statement credit after a qualifying purchase.
The benefit doesn’t require separate activation, but booking conditions and eligibility rules apply.
Is the Hotel Credit Always Worth $100?
The credit’s practical value depends on hotel pricing.
For example, if a hotel costs $220 directly but $250 through Chase Travel, using a $100 credit reduces the portal booking’s effective cost to $150.
That still represents a saving compared with direct booking.
However, travelers should compare room types, cancellation terms, taxes, loyalty benefits, and other booking conditions before deciding.
The credit should not be valued at its full amount when a cardholder would otherwise book a cheaper or more suitable option elsewhere.
5. Everyday Spending Categories Help Earn More Points
The Sapphire Preferred is not limited to earning rewards on flights and hotels.
Its bonus categories include dining, online groceries, streaming subscriptions, gas stations, EV charging, and eligible vacation home rentals.
This makes the card useful between trips, when everyday purchases may account for most spending.
Dining and Grocery Purchases
Eligible dining transactions earn 3x Ultimate Rewards points.
The category generally includes qualifying restaurant purchases and eligible dining services, subject to merchant classification.
Eligible online grocery purchases also earn 3x points, but certain retailers, including Walmart, Target, and wholesale clubs, are excluded.
The distinction between online and in-store grocery purchases matters because not every supermarket transaction qualifies for the accelerated rate.
Gas, EV Charging, and Vacation Rentals
The June 2026 changes added 3x rewards on qualifying gas station and EV charging purchases.
Eligible vacation home rentals through participating brands, including Airbnb and Vrbo, also earn 3x points.
These categories broaden the card’s appeal beyond traditional airline and hotel purchases.
For travelers who frequently book vacation homes or drive during trips, the additional earning opportunities may be particularly useful.
Example of Annual Points Earnings
The following example illustrates how everyday spending could generate rewards.
| Annual Spending Category | Spending | Earning Rate | Points |
| Dining | $3,000 | 3x | 9,000 |
| Eligible online groceries | $2,000 | 3x | 6,000 |
| Gas and EV charging | $1,500 | 3x | 4,500 |
| Other eligible travel | $2,000 | 2x | 4,000 |
| Other purchases | $4,000 | 1x | 4,000 |
| Total | $12,500 | 27,500 |
The example excludes promotional bonuses and assumes all transactions qualify for their respective categories.
The monetary value of 27,500 points depends on how they are redeemed.
Cardholders should avoid spending more than planned merely to earn additional rewards.
6. Chase Travel Points Boost Creates Additional Redemption Opportunities
The Sapphire Preferred also provides access to Points Boost offers through Chase Travel.
Points Boost is a feature that increases the redemption value of Ultimate Rewards points on selected hotel stays and flights.
Eligible Sapphire Preferred redemptions can provide up to 1.5 times the standard point value.
However, these offers are not available on every reservation.
How Does Points Boost Work?
Eligible flights and hotels are identified within the Chase Travel booking platform.
Cardholders can compare the points required for a Points Boost offer against the standard redemption amount.
For example, if an eligible hotel stay costs $300 and a qualifying offer provides a redemption value of 1.5 cents per point, the booking could require 20,000 points.
The same $300 booking at a redemption value of one cent per point would require 30,000 points.
This is an illustrative calculation, not a guaranteed redemption rate for any particular hotel.
Chase states that eligible offers rotate and are subject to availability.
Is Points Boost Better Than Transferring Points?
Not necessarily.
Points Boost can be attractive when an eligible hotel or flight offers a favorable redemption rate.
Transfers may offer greater value when an airline or hotel loyalty program has competitively priced award availability.
A useful comparison considers the cash price, points required, taxes, booking restrictions, and loyalty benefits.
The most valuable redemption is not always the one with the highest advertised multiplier.
7. No Foreign Transaction Fees Make International Spending Easier
The Chase Sapphire Preferred does not charge foreign transaction fees on purchases made outside the United States.
This can help international travelers who regularly pay for hotels, restaurants, transportation, and other expenses in foreign currencies.
Some credit cards charge an additional percentage on foreign transactions, increasing the total cost of overseas spending.
The Sapphire Preferred eliminates that particular card fee.
However, currency conversion rates and merchant-imposed charges can still affect the final amount.
When a merchant offers a choice between paying in US dollars or the local currency, travelers should examine the exchange rate before accepting a conversion.
8. Additional Benefits Can Strengthen the Card’s Value
The Sapphire Preferred includes several benefits beyond its principal travel rewards and insurance features.
Global Entry, TSA PreCheck, or NEXUS Credit
Eligible cardholders can receive up to $120 in statement credits every four years for a qualifying Global Entry, TSA PreCheck, or NEXUS application fee charged to the card.
The benefit is useful for travelers applying for or renewing one of these programs.
However, it should not be treated as an annual $120 credit because it is available once every four years under the stated terms.
DoorDash DashPass Membership
The card offers an eligible complimentary DashPass membership, which may provide reduced delivery charges and additional promotional benefits.
Activation deadlines, participating merchants, order minimums, and membership conditions apply.
The value depends on whether the cardholder already uses the service.
Apple TV Subscription
Chase’s 2026 enhancements introduced a complimentary one-year Apple TV subscription for eligible cardholders who activate the offer by December 31, 2026.
This is a limited-duration benefit rather than a permanent annual subscription.
Purchase Protection and Extended Warranty
The Sapphire Preferred also includes eligible purchase protection and extended warranty benefits.
Purchase protection can cover qualifying new purchases against certain types of theft or damage.
Extended warranty protection may add one year to eligible manufacturer’s US warranties of three years or less.
These features can help with qualifying electronics and other purchases, but exclusions and claim requirements apply.
9. Keeping the Account Open May Support Credit History
Beyond travel rewards, keeping an established credit card account can strengthen a cardholder’s overall credit profile.
Credit scoring models consider several factors, including payment history, amounts owed, account age, and available credit.
Closing an account can reduce available revolving credit, potentially increasing credit utilization if outstanding balances remain unchanged.
For example, a person with $5,000 in total revolving balances and $25,000 in combined credit limits has a 20% utilization ratio.
If a card with a $10,000 limit is closed, the remaining available limit falls to $15,000.
The same $5,000 balance would then represent approximately 33.3% utilization.
However, the impact of closing a credit card varies. Closed accounts in good standing may remain on credit reports for years, so closure does not automatically erase account history or immediately reduce average account age.
Keeping a fee-bearing account solely for credit history may not be worthwhile when a no-annual-fee product change is available.
10. The $95 Annual Fee Is Relatively Manageable
The Sapphire Preferred’s $95 annual fee is substantially lower than the fees charged by some premium travel cards.
That makes it easier to keep for cardholders who benefit from travel protections and transferable points but don’t need luxury airport lounge access.
The fee should still be evaluated against the benefits actually used.
How Much Value Can the Card Provide?
Consider a cardholder who receives the full $100 hotel credit and saves $75 by declining an eligible rental car collision waiver.
The combined potential value is $175.
After subtracting the $95 annual fee, the estimated benefit is $80, before considering points earnings and other protections.
This example assumes the hotel credit is used without paying a higher effective room rate and the rental coverage meets the cardholder’s needs.
Travel insurance benefits are harder to assign a fixed annual value because reimbursement depends on covered events.
A cardholder who rarely travels, rents cars, or uses Chase Travel may receive considerably less value.
Should the Chase Sapphire Preferred Be Closed or Downgraded?
Closing and downgrading a credit card are different decisions.
Closing ends the account, while a product change may let the cardholder switch to another eligible Chase credit card without opening a new account.
A downgrade could help preserve an established credit line while eliminating the annual fee.
However, a no-annual-fee Chase card may not independently provide access to airline and hotel point transfers.
Cardholders should therefore review how a product change affects redemption options, account benefits, and existing points.
What Happens to Ultimate Rewards Points After Closing?
Chase Ultimate Rewards points generally do not expire while an eligible account remains open and in good standing.
However, closing a card can affect the availability of points associated with that account.
Before cancellation, cardholders should consider redeeming eligible points or transferring them to another qualifying Ultimate Rewards account where permitted.
Make transfers to airline or hotel loyalty programs carefully because they are usually final.
Important Chase Sapphire Preferred Changes in 2026
Chase introduced several significant changes on June 15, 2026.
These updates matter because older card reviews may describe benefits that no longer apply.
| Benefit | 2026 Update |
| Annual fee | Remains $95 |
| Chase Travel hotel credit | Increased to $100 |
| Gas and EV charging | Added 3x earning |
| Eligible vacation rentals | Added 3x earning |
| Global Entry, TSA PreCheck, or NEXUS | Added credit of up to $120 every four years |
| Emergency evacuation coverage | Added, subject to conditions |
| World of Hyatt transfers | Changed to 4:3 |
| 10% anniversary points bonus | Discontinued for new applicants from June 15, 2026 |
Existing eligible cardholders retained the 10% anniversary bonus on qualifying purchases made through October 1, 2026, with applicable bonuses scheduled for award by January 31, 2027.
The revised World of Hyatt transfer ratio became effective October 1, 2026, for cardholders who applied before June 15, 2026.
These changes show why you should review long-term credit card value periodically rather than judge it solely by historical benefits.
Final Thoughts
The Chase Sapphire Preferred remains a strong long-term option for travelers who value primary rental car coverage, travel insurance, and flexible Ultimate Rewards redemptions.
Its $95 annual fee is relatively manageable, especially when cardholders use the annual hotel credit and other benefits effectively.
However, whether to keep the card should depend on actual spending and travel habits rather than the value of its original welcome offer.
Cardholders should review their annual benefit usage, compare alternative cards, and verify the latest Chase terms before renewing, downgrading, or closing the account.
Frequently Asked Questions
The card can be worth keeping if its travel protections, transferable points, bonus categories, and hotel credit outweigh the $95 annual fee.
No. The Chase Sapphire Preferred does not include complimentary airport lounge access as a standard card benefit.
Yes. Eligible Ultimate Rewards points can be transferred to participating airline loyalty programs, generally at a 1:1 ratio.
The card provides primary rental car collision coverage for eligible rentals in the United States and most other countries. Vehicle exclusions, rental conditions, and other limitations apply.
Closing the account may affect credit utilization and other credit factors. The actual impact depends on the cardholder’s overall credit profile.
Eligible cardholders may be able to request a product change to another Chase credit card. Available options and eligibility must be confirmed directly with Chase.