Chase Sapphire Reserve vs Amex Platinum: Key Differences
The Chase Sapphire Reserve and The Platinum Card from American Express are both premium U.S. travel cards. Still, they are built around different reward structures, credits, lounge networks, and travel benefits, so the better card depends on how a cardholder spends and which benefits they can realistically use. As of September 2026, the Sapphire Reserve carries a $795 annual fee, while the Amex Platinum carries an $895 annual fee.
This comparison focuses on the U.S.-issued consumer versions of both cards. It covers annual fees, welcome offers, rewards, travel credits, airport lounges, hotel benefits, travel protections, transfer partners, everyday spending, redemption options, and the practical differences that matter after year one.
Important: Credit-card benefits, welcome offers, transfer partners, fees, and promotional credits can change. The figures below reflect issuer information available in September 2026. Terms and eligibility requirements apply.
Chase Sapphire Reserve vs. Amex Platinum: Quick Comparison
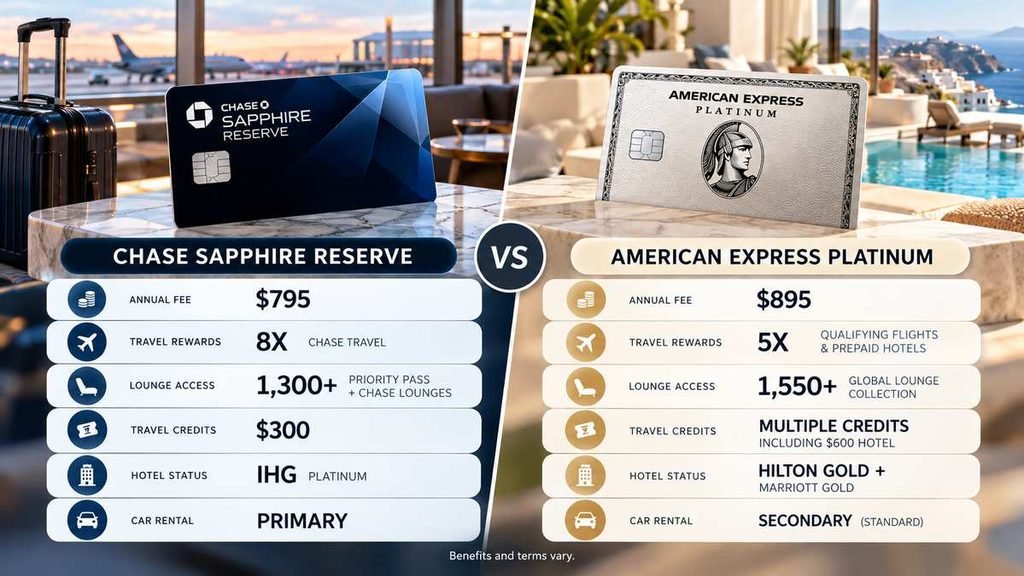
The Chase Sapphire Reserve and American Express Platinum are premium travel cards with different strengths. The Sapphire Reserve emphasizes flexible travel credits, Chase Travel rewards, and lounge access, while the Amex Platinum focuses heavily on premium travel, hotel, airline, and lifestyle benefits. Fees, rewards, credits, and eligibility vary, so travelers should compare the benefits they can realistically use.
| Feature | Chase Sapphire Reserve | Amex Platinum |
| Annual fee | $795 | $895 |
| Authorized-user fee | $195 each | $195 each |
| Main rewards currency | Chase Ultimate Rewards | Membership Rewards |
| Flights | 4X when booked directly | 5X directly with airlines or through Amex Travel, up to $500,000/year |
| Hotels | 4X when booked directly | 5X on prepaid hotels through Amex Travel |
| Chase/Amex travel portal | 8X through Chase Travel | 5X on qualifying flights and prepaid hotels |
| Other eligible purchases | 1X | 1X |
| Lounge network | Chase Sapphire Lounges + 1,300+ Priority Pass lounges; select Air Canada lounges | 1,550+ lounges through Global Lounge Collection |
| Annual travel credit | $300 broad travel credit | Multiple targeted credits, including $600 hotel credit |
| Global Entry/TSA PreCheck/NEXUS | Up to $120 every 4 years | Up to $120 every 4 years for Global Entry or up to $85 for TSA PreCheck |
| Hotel status | IHG One Rewards Platinum Elite; other promotional benefits may apply | Hilton Gold and Marriott Gold |
| Foreign transaction fees | None | None |
| Rental-car coverage | Primary, up to $75,000 for covered theft/collision | Standard coverage is secondary; Premium Car Rental Protection is an optional paid enrollment |
| Travel protections | Extensive built-in coverage | Trip, baggage and rental protections with separate terms |
| Point transfers | Airline and hotel partners | Airline and hotel partners |
The rewards categories and benefits are subject to detailed terms, eligibility rules, and changing promotional periods.
Annual Fee and Overall Cost
The annual fee is one of the clearest differences.
The Chase Sapphire Reserve costs $795 per year, with a $195 annual fee for each authorized user. The card currently advertises a 100,000-point welcome offer after $6,000 in purchases during the first three months for eligible new cardmembers.
The Amex Platinum costs $895 per year, and each Additional Platinum Card also costs $195. American Express’ welcome offers can vary by application, eligibility, and promotional period, so applicants should verify the offer displayed on the official application page rather than relying on an older advertised bonus.
The $100 difference in annual fee does not tell the whole story. Both cards attach substantial value to credits and travel benefits, but those benefits work differently.
For example, a traveler who naturally spends on airfare, qualifying hotels, dining, and travel may find it easier to use some Sapphire Reserve credits without changing normal purchasing habits. The Platinum card, meanwhile, has a larger collection of credits that can be valuable when the cardholder already uses eligible services such as Uber, Resy, and participating hotel programs.
Chase Sapphire Reserve Rewards vs. Amex Platinum Rewards
The earning structures are significantly different.
Chase Sapphire Reserve earning structure
The Sapphire Reserve currently earns:
- 8X Ultimate Rewards points on purchases through Chase Travel
- 4X points on flights booked directly
- 4X points on hotels booked directly
- 3X points on dining worldwide
- 1X point on other eligible purchases
The distinction between direct bookings and Chase Travel matters. A traveler booking a $1,000 flight directly with an airline would earn 4,000 points, while an eligible $1,000 Chase Travel purchase could earn 8,000 points.
The card also has Points Boost, which can make points worth up to 2 cents each on selected hotels and flights booked through Chase Travel. These offers rotate and are not available on every booking.
Amex Platinum earning structure
The Platinum Card earns:
- 5X Membership Rewards points on flights booked directly with airlines or through Amex Travel, on up to $500,000 of eligible purchases per calendar year
- 5X points on prepaid hotels booked through Amex Travel
- 1X point on other eligible purchases
This creates an important practical difference.
Someone spending heavily on airfare may accumulate points quickly with the Platinum Card. However, the card’s standard 1X rate on most everyday purchases means it rewards miscellaneous spending less than some other cards in a broader rewards strategy.
The Sapphire Reserve offers 3X on dining, which can matter for travelers who frequently charge restaurant spending to the card.
Chase Ultimate Rewards vs. Amex Membership Rewards
Both cards use transferable rewards currencies rather than locking cardholders into a single airline.
Chase Ultimate Rewards
Sapphire Reserve cardmembers can transfer Ultimate Rewards points to participating airline and hotel programs. Chase lists partners including Air Canada Aeroplan, British Airways, Flying Blue, Iberia, JetBlue, Singapore Airlines, Southwest, Virgin Atlantic, IHG One Rewards, Marriott Bonvoy, World of Hyatt, and Wyndham Rewards. Most listed partners use a 1:1 transfer ratio, although World of Hyatt’s ratio changed for certain newer accounts in 2026.
This flexibility can help travelers compare several airline programs before transferring points.
American Express Membership Rewards
Amex Membership Rewards points can also be transferred to participating airline and hotel loyalty programs. American Express warns that transfers are final, so travelers should verify award availability before moving points.
The value of Membership Rewards therefore depends heavily on how the cardholder redeems them. Someone who transfers points strategically to an airline program may use them differently than someone who applies them toward travel through Amex Travel.
Practical example: If a traveler needs 60,000 airline miles for an award ticket, it is generally preferable to confirm the award seat first and then transfer the required points rather than transferring speculatively.
Travel Credits: How the Cards Differ
Travel credits are central to both cards’ economics, but their structures differ.
Sapphire Reserve travel credits
The Sapphire Reserve provides a $300 annual travel credit that automatically reimburses qualifying travel purchases. Unlike credits restricted to one merchant or booking platform, the eligible travel category includes a broad range of expenses.
The card also offers a $500 annual credit for prepaid stays through The Edit by Chase Travel, subject to the benefit’s booking and two-night minimum requirements. In 2026, the card also includes a temporary $250 credit for qualifying prepaid two-night stays at select hotel groups through Chase Travel.
Other 2026 benefits include:
- Up to $300 in dining credits through eligible Sapphire Exclusive Tables restaurants
- Up to $120 in Lyft credits
- DoorDash DashPass and eligible promotional credits
- Up to $300 in StubHub/viagogo credits
- Apple TV and Apple Music benefits
- Peloton credits and bonus points
Some of these benefits require activation, have monthly or semiannual limits, or are temporary.
Amex Platinum credits
The Platinum Card has a much larger collection of targeted credits. Current benefits include:
- Up to $600 in annual hotel credits on eligible prepaid Fine Hotels + Resorts or The Hotel Collection bookings through Amex Travel
- Up to $200 in Uber Cash
- Up to $120 in Uber One credits
- Up to $400 in Resy credits
- Up to $300 in digital entertainment credits
- Up to $300 in lululemon credits
- Up to $219 in CLEAR+ credits
- Global Entry/TSA PreCheck-related credits and other benefits
Many of these credits require enrollment and may have monthly or quarterly caps, merchant restrictions, or U.S.-only eligibility.
That distinction matters: a credit’s advertised dollar amount isn’t automatically equivalent to cash value for every cardholder. If someone rarely uses Resy, Uber, qualifying hotels, or the listed entertainment services, the theoretical value of those credits may be much lower in practice.
Airport Lounge Access Compared
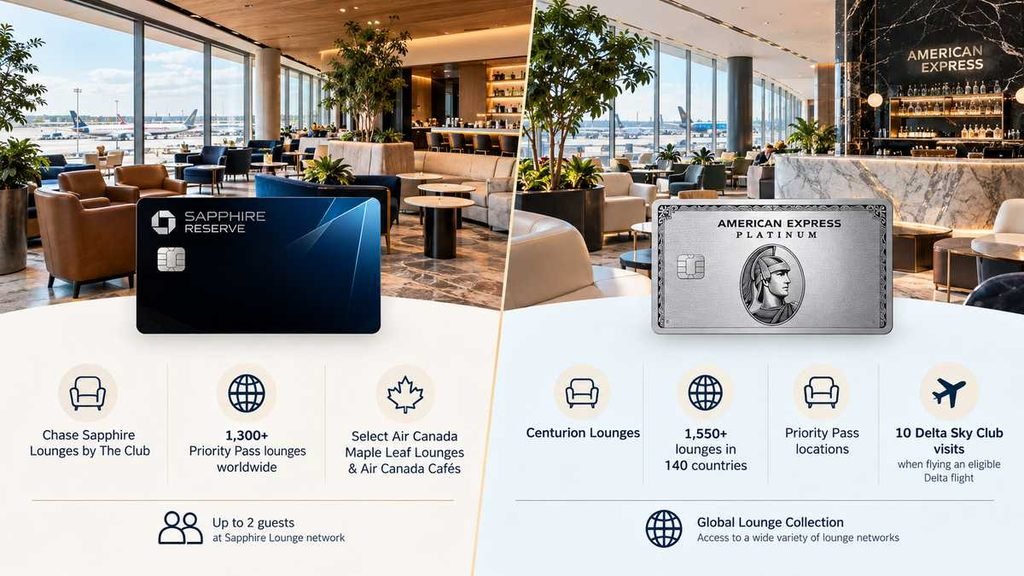
Airport lounges are a major part of both cards, but their networks differ.
Sapphire Reserve lounge access
The Sapphire Reserve provides access to Chase Sapphire Lounges by The Club, more than 1,300 Priority Pass lounges worldwide, and select Air Canada Maple Leaf Lounges and Air Canada Cafés with an eligible boarding pass. Cardmembers can bring up to two guests into the Sapphire Reserve lounge network under the applicable terms.
This is especially relevant at airports where Chase has a Sapphire Lounge.
Amex Platinum lounge access
The Amex Platinum offers access to more than 1,550 airport lounges across 140 countries, including Centurion Lounges, Priority Pass locations and other partner lounges. Eligible Platinum members can also receive 10 Delta Sky Club visits when flying an eligible Delta flight, subject to program rules.
The larger Global Lounge Collection gives Platinum cardholders access to a wide variety of networks.
However, travelers should check which lounges are available at their regular airports. A larger published network does not necessarily mean the most convenient lounge for a particular traveler.
Hotel Benefits and Elite Status
Hotel benefits are another key difference.
The Sapphire Reserve includes IHG One Rewards Platinum Elite status, with the current benefit extending through December 31, 2027 under the issuer’s terms. Other hotel-related promotions can be temporary.
The Amex Platinum provides Marriott Bonvoy Gold Elite and Hilton Honors Gold status, subject to enrollment and program terms. It also provides access to Fine Hotels + Resorts and The Hotel Collection, where eligible bookings can include benefits such as breakfast, property credits, late checkout, and potential upgrades.
For example, a traveler who regularly stays at Hilton properties may place more practical importance on Hilton Gold than on a hotel credit that requires a specific booking channel.
Travel Insurance and Purchase Protections
The Sapphire Reserve has particularly detailed built-in travel protections.
Current benefits include:
- Trip cancellation/interruption coverage of up to $10,000 per covered traveler and $20,000 per trip
- Trip delay reimbursement of up to $500 per covered traveler after qualifying delays
- Primary rental-car coverage up to $75,000 for covered theft and collision
- Emergency evacuation and transportation coverage
- Baggage delay coverage
- Travel accident insurance
The Sapphire Reserve’s primary rental-car coverage is a notable feature. Travelers generally need to decline the rental company’s collision coverage and charge the full rental cost to the card, subject to the policy’s exclusions and conditions.
The Amex Platinum also provides trip cancellation/interruption, trip delay, and baggage insurance, plus rental-car coverage. Its standard Car Rental Loss and Damage Insurance is secondary, while American Express also offers a separate Premium Car Rental Protection program that can provide primary coverage after enrollment.
This makes it important to read the exact benefit terms before assuming that two cards offer identical insurance.
Which Card Has Better Everyday Earning Potential?
The answer depends on what “everyday” means for the cardholder.
The Sapphire Reserve’s 3X worldwide dining category provides a recurring bonus category outside travel. Its 1X base rate applies to most other purchases.
The Amex Platinum earns 1X on general purchases, while concentrating its strongest earning rates on flights and prepaid hotels booked through the qualifying channels.
For example:
- $5,000 in eligible dining on Sapphire Reserve → 15,000 points
- $5,000 in ordinary non-bonus purchases on either card → generally 5,000 points
- $5,000 in eligible airfare on Amex Platinum → 25,000 Membership Rewards points
The actual value of those points depends on how you redeem them, so comparing point totals alone isn’t enough.
Acceptance and International Travel
Both cards have no foreign transaction fees. Chase states that Sapphire Reserve can be used internationally without foreign transaction fees and emphasizes its broad global acceptance. American Express also states that the Platinum Card has no foreign transaction fees.
The important distinction is merchant acceptance, not the foreign transaction fee.
American Express acceptance has expanded considerably, but travelers going to smaller merchants or destinations where Amex acceptance is less consistent may want a Visa or Mastercard as a backup. The Sapphire Reserve is a Visa card and can therefore serve as an alternative payment method when Amex isn’t accepted.
For an international trip, carrying a second payment card is sensible regardless of which premium card is the primary card.
Authorized Users: An Important Cost Difference
Both cards charge $195 per additional premium card, making this a significant consideration for households.
The value of an additional card depends largely on how the household uses lounge access, travel benefits, and other account-level perks.
Before adding an authorized user, a cardholder should check whether the benefit applies individually to that additional cardmember, whether guests are included, and whether the relevant benefit requires enrollment.
Chase Sapphire Reserve vs. Amex Platinum: Which Features Matter Most?
Instead of treating either card as universally superior, travelers can compare the cards according to their actual usage.
| If the cardholder prioritizes… | Relevant features to examine |
| Flexible travel purchases | Sapphire Reserve’s $300 broad travel credit |
| Chase Travel bookings | Sapphire Reserve’s 8X earning and Points Boost |
| Direct airfare | Amex Platinum 5X vs. Sapphire Reserve 4X |
| Direct hotel bookings | Sapphire Reserve 4X |
| Prepaid Amex Travel hotels | Platinum 5X |
| Restaurant spending | Sapphire Reserve 3X dining |
| Broad lounge network | Amex Global Lounge Collection |
| Chase Sapphire Lounges | Sapphire Reserve |
| Hilton and Marriott status | Amex Platinum |
| IHG status | Sapphire Reserve |
| Primary rental-car coverage | Sapphire Reserve |
| Uber and Resy credits | Amex Platinum |
| Multiple lifestyle credits | Amex Platinum |
| Simple travel-credit structure | Sapphire Reserve |
| Transferable airline/hotel points | Both |
This framework is more useful than comparing advertised annual benefit totals alone because many premium-card credits are conditional.
Common Mistakes When Comparing These Cards
Counting every credit at face value
A $400 credit is only worth $400 if the cardholder would otherwise spend $400 on eligible purchases.
Ignoring activation requirements
Several Amex and Chase benefits require enrollment or activation. Missing that step can prevent a cardholder from receiving the benefit.
Comparing points without considering redemption
One Membership Rewards point and one Ultimate Rewards point are not automatically worth the same amount in every redemption.
Assuming lounge access is identical
Both cards offer extensive lounge access, but the networks, guest rules and participating locations differ.
Ignoring booking channels
The difference between booking directly with an airline, through Chase Travel, or through Amex Travel can affect both points earned and eligibility for credits.
Forgetting that benefits can expire or change
Some 2026 benefits are promotional and have stated end dates. Cardholders should review the current benefit dashboard before planning around a temporary credit.
Final Takeaway
The Chase Sapphire Reserve and Amex Platinum are premium travel cards with overlapping features but different structures. Sapphire Reserve combines a broad $300 travel credit, strong dining and direct-travel earning, Chase Travel rewards, Points Boost, and substantial travel protections. Amex Platinum places greater emphasis on premium lounge access, airfare earning, hotel programs, and a large collection of lifestyle and travel credits.
The practical comparison should therefore start with actual spending rather than advertised benefit totals. Travelers should examine where they fly, which airports they use, whether they stay with Hilton, Marriott or IHG, how often they use Uber or Resy, how much they spend on dining and airfare, and whether they value primary rental-car coverage.
Before applying, applicants should also verify the current welcome offer, annual fee, benefit terms, transfer partners, and eligibility requirements directly with Chase or American Express, because premium-card benefits can change.
Frequently Asked Questions
Yes. As of September 2026, the Sapphire Reserve has a $795 annual fee, compared with $895 for the Amex Platinum. Both charge $195 for each authorized user.
There is no single answer because the earning categories differ. Sapphire Reserve earns 3X on worldwide dining and 4X on directly booked flights and hotels, while Amex Platinum earns 5X on eligible flights and prepaid Amex Travel hotels.
The two cards use different lounge networks. Amex Platinum provides access to more than 1,550 lounges through its Global Lounge Collection, while Sapphire Reserve provides Chase Sapphire Lounge access and 1,300+ Priority Pass lounges, among other access. The most useful network depends on the airports and airlines a traveler actually uses.
The Sapphire Reserve’s $300 credit is broad and automatically applies to qualifying travel purchases. Amex Platinum instead distributes value across several more specialized credits, including its $600 hotel credit. The practical value depends on spending patterns.
Yes. Both Chase Ultimate Rewards and American Express Membership Rewards can transfer points to participating airline and hotel loyalty programs. The available partners and transfer ratios vary by program and can change over time.
The Sapphire Reserve includes primary rental-car coverage of up to $75,000 for covered theft and collision, provided you meet the applicable requirements. Standard Amex Platinum rental-car loss and damage coverage is secondary, although Amex offers a separate Premium Car Rental Protection option.
Yes. The U.S. Platinum Card has no foreign transaction fees, and American Express has a global merchant network. However, acceptance can vary by merchant and destination, so travelers may want to carry a backup Visa or Mastercard.
No. They are separate rewards programs with different transfer partners, redemption systems, and program rules. Both can transfer to participating airline and hotel programs, but you shouldn’t treat points as interchangeable.
They can, but the annual-fee calculation matters more. A traveler who cannot naturally use the available travel, hotel, dining, lounge, or lifestyle benefits may not capture enough value to justify a premium annual fee.