Comenity Bank Credit Cards: Complete List of 120+ Store Cards in 2026
Comenity Bank and Comenity Capital Bank issue or service more than 120 retail, co-branded, and specialty credit card products associated with brands ranging from Victoria’s Secret and Lane Bryant to Ulta Beauty, Sephora, KAY Jewelers, Toyota, and Caesars Rewards. Many are closed-loop store cards, while others carry Visa, Mastercard, or American Express branding and can be used more broadly.
Comenity is part of Bread Financial, a financial-services company that specializes heavily in private-label and co-branded credit programs.
Store cards are sometimes described as easier to qualify for than general-purpose rewards cards. However, that should not be interpreted as guaranteed approval or as meaning every Comenity card accepts applicants with poor credit. Approval criteria vary by product and applicant, and issuers generally consider information such as credit history, income, existing debt, and overall creditworthiness.
There is another important development for 2026: Bread Financial has received regulatory approval to merge Comenity Bank into Comenity Capital Bank, with Comenity Capital Bank surviving the transaction. Bread Financial said in September 2026 that it expected the merger to occur on or around October 1, 2026, subject to the remaining conditions.
As a result, cardholders and applicants may see issuer names change as Bread Financial updates its banking structure.
Comenity Bank Credit Cards at a Glance
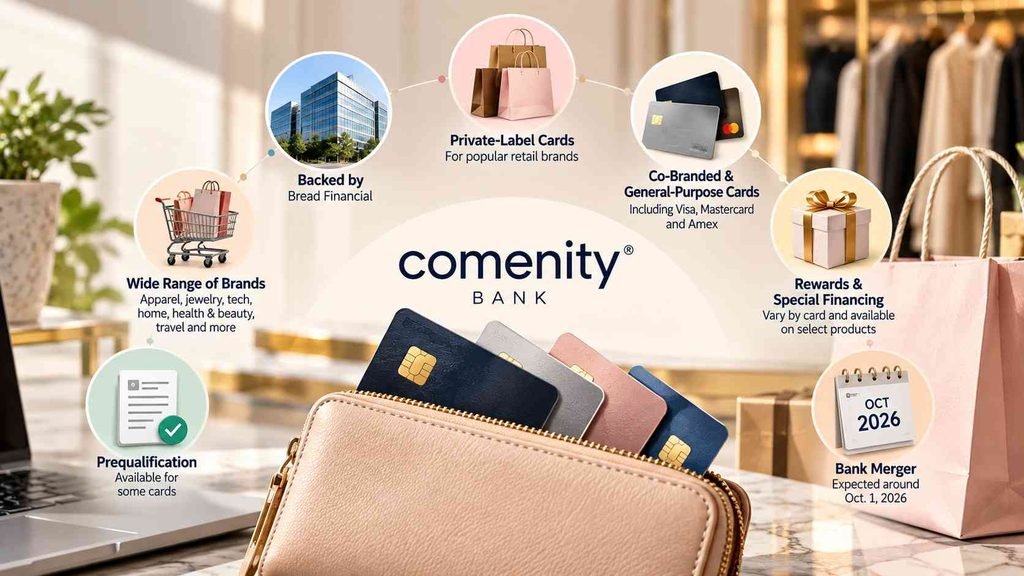
Bread Financial says its broader payments business serves recognized brands across categories including apparel, jewelry, technology, electronics, home, health and beauty, and travel and entertainment.
| Feature | Details |
| Parent company | Bread Financial |
| Bank names | Comenity Bank and Comenity Capital Bank |
| Major product type | Private-label/store credit cards |
| Other products | Co-branded and general-purpose cards |
| Store-only cards | Yes |
| Visa/Mastercard/Amex cards | Yes |
| Rewards | Vary by card |
| Special financing | Available on selected products |
| Approval guaranteed | No |
| Prequalification | Available for some products |
| Typical best use | Frequent purchases with a specific retailer |
| Bank merger | Expected around Oct. 1, 2026 |
What Is Comenity Bank?
Comenity Bank is a Bread Financial banking subsidiary best known for issuing private-label and co-branded credit cards for retailers and other consumer brands.
You may therefore have a Comenity account without seeing “Comenity” prominently displayed on the front of your card.
For example, the card may carry the name of a:
- Clothing retailer
- Jewelry company
- Beauty retailer
- Furniture brand
- Sporting-goods company
- Automotive brand
- Travel or entertainment program
Comenity handles the underlying credit relationship for many such accounts.
Bread Financial’s current business extends beyond traditional store cards to include co-branded cards, general-purpose credit cards, savings products, and pay-over-time financing.
Are Comenity Bank and Bread Financial the Same?
Comenity Bank is part of Bread Financial, but the names do not refer to exactly the same legal entity.
Bread Financial Holdings is the parent financial-services company.
Its banking subsidiaries have included:
Comenity Bank
and
Comenity Capital Bank
Bread Financial has also increasingly used its own name publicly, which explains why customers may encounter both “Comenity” and “Bread Financial” while managing an account.
Comenity Bank Is Changing in 2026
This distinction is particularly important right now.
Bread Financial disclosed in September 2026 that it had received the necessary regulatory approvals to merge Comenity Bank into Comenity Capital Bank.
The company expected the transaction to close on or around October 1, 2026.
Once completed, Comenity Capital Bank will be the surviving bank.
That means a 2026 list dividing products permanently into “Comenity Bank cards” and “Comenity Capital Bank cards” can quickly become outdated.
Existing cardholders should follow official notices from Bread Financial or their specific card program rather than assuming they need to take action because the legal issuer changes.
Complete List of Comenity Store Credit Cards
The following directory covers private-label and specialty card programs associated with Comenity Bank or Comenity Capital Bank in the 2026 portfolio.
Card programs can be added, discontinued, renamed, transferred between issuers, or converted to new products. Always confirm availability before applying.
Comenity Store Cards: A–C
| Store/Card Program |
| Academy Sports + Outdoors Credit Card |
| All Pet Credit Card |
| Alphaeon Cosmetic Credit Card |
| Alphaeon Vision Credit Card |
| Ann Taylor Credit Card |
| Arhaus Archarge |
| Ashley Stewart Credit Card |
| Avenue Credit Card |
| B&H Payboo Credit Card |
| Ballard Designs Credit Card |
| Banter Credit Card |
| Bealls Credit Card |
| Bed Bath & Beyond Credit Card |
| Big Lots Credit Card |
| Big O Tires and Service Credit Card |
| Blue Nile Credit Card |
| Boot Barn Credit Card |
| Boscov’s Credit Card |
| BrylaneHome Platinum Credit Card |
| Bucherer 1888 Credit Card |
| Buckle Credit Card |
| Burlington Credit Card |
| Carter’s Credit Card |
| Catherines Credit Card |
| Cosmo Prof Rewards Credit Card |
The Consumer Financial Protection Bureau’s current agreement database confirms several Comenity Capital Bank products in this portion of the alphabet, including Ballard Designs, Banter, Bed Bath & Beyond, B&H Payboo, Big Lots, Big O Tires, and Blue Nile.
Comenity Store Cards: D–H
| Store/Card Program |
| Dell Pay Credit Account |
| El Dorado Furniture BLUCard |
| Express Credit Card |
| Famous Footwear FAMOUSLY YOU REWARDS Credit Card |
| Frontgate Credit Card |
| fullbeauty Platinum Credit Card |
| GameStop Pro Credit Card |
| GEM Account Credit Card |
| Good Sam Credit Card |
| Gordon’s Jewelers Credit Card |
| Grandin Road Credit Card |
| Harley-Davidson Experience Credit Card |
| HealthiPlan Patient Financing |
| Helzberg Credit Card |
| Hot Topic Guest List Credit Card |
| HP Credit Account |
Some of these products function more like retail financing accounts than conventional rewards credit cards.
That distinction matters because financing terms can be considerably more important than rewards.
Comenity Store Cards: I–M
| Store/Card Program |
| Iddeal Credit Card |
| IKEA Projekt Credit Card |
| Interval World Mastercard Credit Card |
| Jared Preferred Credit Card |
| J.Crew Credit Card |
| Jessica London Platinum Credit Card |
| J.Jill Credit Card |
| KAY Jewelers Credit Card |
| KingSize Platinum Credit Card |
| Lands’ End Credit Card |
| Lane Bryant Credit Card |
| Legendary Pine Mastercard |
| Lexus Pursuits Credit Card |
| Little Switzerland Credit Card |
| LOFT Credit Card |
| maurices Credit Card |
| Michaels Credit Card |
| Midas Credit Card |
| My Place Rewards Credit Card |
| My Smile Care Program Credit |
The CFPB’s current Comenity Bank agreement database confirms active agreements for products including J.Crew, Jessica London Platinum, KAY Jewelers, KingSize Platinum, Lane Bryant, Little Switzerland, and LOFT.
Comenity Store Cards: N–S
| Store/Card Program |
| Nest Credit Card |
| New York & Company RUNWAYREWARDS Credit Card |
| Petco Pay Credit Card |
| Petland Credit Card |
| Points Power Mastercard |
| Raymour & Flanigan Credit Account |
| Roaman’s Platinum Credit Card |
| Ross Credit Card |
| Saks Credit Card |
| Sally Beauty Rewards Credit Card |
| SalonCentric Credit Card |
| Sephora Credit Card |
| Smile Generation Financial |
| Sportsman’s Guide Explorewards Credit Card |
| Sterling Family of Jewelers Credit Card |
Bread Financial took over the Saks Fifth Avenue and Saks OFF 5TH private-label and co-branded credit program through Comenity Capital Bank beginning in 2024.
Comenity Store Cards: T–Z
| Store/Card Program |
| Talbots Credit Card |
| The World Market Credit Card |
| Torrid Credit Card |
| Toyota Credit Card |
| TRENDSETTER REWARDS Credit Card |
| Ulta Beauty Rewards Credit Card |
| Victoria’s Secret Credit Card |
| Woman Within Platinum Credit Card |
| Your Tuition Solution Credit |
| Zales Credit Card |
| Zales Outlet Credit Card |
Current CFPB records include Comenity Bank agreements for TRENDSETTER REWARDS, Victoria’s Secret, and Woman Within, among others.
Ulta Beauty, meanwhile, identifies Comenity Capital Bank as the current issuer of its Ulta Beauty Rewards Credit Card.
Comenity Visa, Mastercard, and American Express Cards
Not every Comenity-issued card is restricted to one retailer.
Some products are open-loop cards, meaning they operate on a major payment network and can generally be used wherever that network is accepted.
Examples in the 2026 portfolio include:
| Credit Card |
| AAA Daily Advantage Visa Signature Credit Card |
| AAA Travel Advantage Visa Signature Credit Card |
| Ann Taylor Mastercard |
| Bread Cashback American Express Credit Card |
| Bread Rewards American Express Credit Card |
| Caesars Rewards Prestige Visa Signature Credit Card |
| Caesars Rewards Visa Credit Card |
| Coast to Coast Visa Credit Card |
| Comenity Mastercard Credit Card |
| Crypto.com Visa Signature Credit Card |
| Green Bay Packers Extra Points Mastercard |
| IKEA Visa Credit Card |
| Lands’ End Visa Credit Card |
| Lexus Pursuits Visa Credit Card |
| LOFT Mastercard Credit Card |
| My World Mastercard Credit Card |
| New York Yankees Mastercard Credit Card |
| NFL Extra Points Visa Credit Card |
| PENN Entertainment Mastercard Credit Card |
| Petco Pay Mastercard |
| PlayStation Visa Credit Card |
| Ross Mastercard Credit Card |
| Saks World Elite Mastercard |
| Sephora Visa |
| Sportsman’s Guide Buyer’s Club Rewards Visa |
| Sportsman’s Guide Explorewards Visa |
| Talbots Mastercard |
| Toyota Rewards Visa Credit Card |
| Ulta Beauty Rewards Mastercard |
| Unity by Hard Rock Mastercard |
| Victoria’s Secret Mastercard |
| Worldwide Vacation & Travel Mastercard |
These cards should not be confused with store-only versions carrying a similar name.
For example, Ulta currently offers both:
Ulta Beauty Rewards Credit Card — usable at eligible Ulta Beauty locations and ulta.com.
Ulta Beauty Rewards Mastercard — usable at Ulta Beauty and anywhere Mastercard is accepted.
Ulta confirms that both are currently issued by Comenity Capital Bank.
Store Card vs. Open-Loop Comenity Card
The difference is important before applying.
| Feature | Store Card | Open-Loop Card |
| Where it works | Specific retailer/brand network | Wherever network is accepted |
| Visa/Mastercard/Amex logo | Usually no | Yes |
| Retail rewards | Often | Often |
| Everyday spending | Limited | Possible |
| Approval guaranteed | No | No |
| Credit check | Usually required | Usually required |
| Financing offers | Common on some cards | Varies |
| General rewards | Usually limited | More likely |
A closed-loop card can still be useful if nearly all of its value comes from a retailer you frequently use.
The broader acceptance of an open-loop card does not automatically make it the better product.
Are Comenity Bank Cards Easy To Get Approved For?
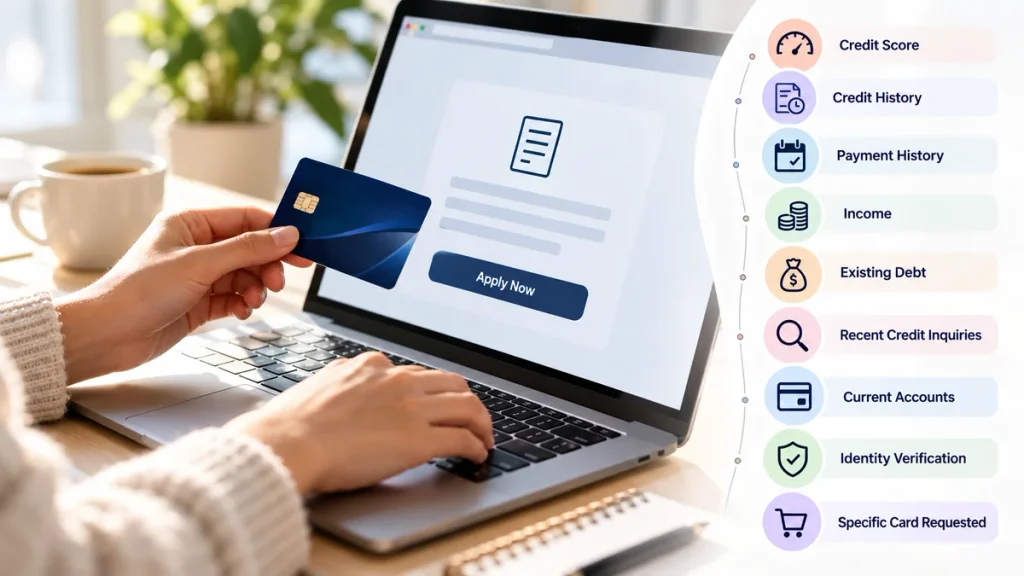
Some Comenity retail cards may be accessible to applicants with less-established credit profiles, but there is no universal “easy approval” Comenity card and approval is never guaranteed.
The reference article describes Comenity cards generally as easier to get approved for than some alternatives. However, consumers should not interpret that as a published minimum-credit-score policy applying to the entire portfolio.
Different card programs can use different underwriting criteria.
Factors that may influence approval include:
- Credit score
- Credit history
- Payment history
- Income
- Existing debt
- Recent credit inquiries
- Current accounts
- Identity verification
- The specific card requested
A store-only card may have different underwriting characteristics from an open-loop Visa or Mastercard.
But only the issuer can decide whether a particular applicant qualifies.
What Credit Score Do You Need for a Comenity Card?
Comenity does not publish one minimum credit score that guarantees approval across all of its credit cards.
Avoid claims such as:
“You need exactly a 640 credit score.”
or:
“Anyone with fair credit will be approved.”
Neither statement can reliably apply to more than 100 different credit products.
Even applicants with the same credit score can receive different decisions because lenders consider more than the score itself.
Can You Get a Comenity Card With Bad Credit?
Possibly, depending on the card and your overall credit profile, but there is no guarantee.
Retail cards have historically been popular among consumers building credit partly because some store-card underwriting can differ from that of premium rewards cards.
Still, an applicant can be declined.
Someone with severely damaged credit may want to compare:
- Secured credit cards
- Credit-builder products
- Cards offering prequalification
- Store cards they would genuinely use
Do not repeatedly submit applications simply because a card has been described online as “easy approval.”
Each application can have credit implications.
Which Comenity Cards Are Considered Easier To Qualify For?
There is no authoritative Comenity list ranking its cards from easiest to hardest approval.
Instead, consumers looking for potentially more accessible options can focus on private-label store cards rather than assuming a co-branded Visa or Mastercard will have identical underwriting.
Examples of store-only programs include cards associated with retailers such as:
- Lane Bryant
- Torrid
- Victoria’s Secret
- J.Crew
- KAY Jewelers
- Ulta Beauty
- Burlington
- Buckle
These are examples of private-label or retailer-focused cards, not guaranteed easy-approval recommendations.
Approval remains subject to the issuer’s credit decision.
Can You Prequalify for a Comenity Credit Card?
Some Comenity/Bread Financial card programs may offer prequalification or pre-screened application experiences, but availability varies by product.
If a prequalification option is available, read its disclosure carefully.
Prequalification generally means the issuer can evaluate certain information to estimate whether you may qualify.
It does not mean:
Guaranteed approval.
A full application may involve additional verification and a hard credit inquiry.
Does Prequalification Hurt Your Credit?
A genuine prequalification process often uses a soft credit inquiry, which generally does not affect credit scores.
A formal credit-card application can result in a hard inquiry.
However, do not assume every application page follows the same process.
Read the disclosure presented before submitting personal information.
Popular Comenity Store Cards To Know About
Rather than ranking the cards as universally “best,” it is more useful to understand why certain programs may appeal to loyal customers.
Ulta Beauty Rewards Credit Card
The Ulta Beauty Rewards Credit Card is a private-label card designed for Ulta shoppers.
Ulta currently states that cardmembers earn additional rewards on qualifying Ulta purchases.
The store card can only be used with eligible Ulta Beauty purchases, while the Mastercard version can be used wherever Mastercard is accepted.
Both are issued by Comenity Capital Bank.
The important lesson is to determine which version you are applying for.
Victoria’s Secret Credit Card
The Victoria’s Secret program offers both a store credit card and a Mastercard version.
Current CFPB records identify agreements for both the Victoria’s Secret Credit Card and Victoria’s Secret Mastercard under Comenity Bank.
The store card is primarily relevant to frequent Victoria’s Secret and PINK shoppers.
Lane Bryant Credit Card
The Lane Bryant Credit Card is another retailer-focused Comenity product.
Lane Bryant currently confirms that its credit card accounts are issued by Comenity Bank.
One major consideration is interest.
The September 2026 card agreement lists a 35.99% purchase APR, illustrating why store-card rewards can quickly be outweighed by interest when balances are carried.
J.Crew Credit Card
J.Crew is included in the CFPB’s current database of Comenity Bank credit-card agreements.
Like other retailer-specific cards, its usefulness depends primarily on how frequently a cardholder shops with the associated brand and whether the current benefits justify opening another account.
KAY Jewelers Credit Card
The KAY Jewelers Credit Card is another current Comenity Bank product listed in the CFPB database.
Jewelry cards can advertise promotional financing arrangements.
Pay particular attention to:
- Promotional period
- Minimum payments
- Purchase requirements
- Standard APR
- What happens if the balance remains after the promotional period
Never assume “special financing” means the purchase is permanently interest-free.
Torrid Credit Card
The Torrid Credit Card is a retailer-focused card intended for frequent Torrid shoppers.
Its value depends primarily on current Torrid cardholder discounts, rewards, and shopping frequency.
As with any store card, compare the savings with the card’s APR before carrying a balance.
Sephora Credit Card and Sephora Visa
The Sephora program has included both:
Sephora Credit Card
and
Sephora Visa
The difference is similar to other dual-product programs.
The private-label version is retailer-focused, while the Visa can be used wherever Visa is accepted.
What Is the Comenity Mastercard?
Comenity also offers a general-purpose Comenity Mastercard rather than tying every product to a specific retailer.
The current September 2026 agreement confirms that the card is issued by Comenity Bank.
The agreement shows that purchase APRs can vary according to the account’s assigned pricing.
This is another reason applicants should read their own rate-and-fee disclosure rather than relying on a generic Comenity APR.
Why Do Retailers Use Comenity?
Retailers partner with issuers such as Comenity because private-label cards can encourage repeat purchases and integrate financing or rewards into the retailer’s loyalty program.
Bread Financial describes private-label credit cards as products designed to drive customer loyalty and increase spending with a brand.
For customers, potential advantages can include:
- Store discounts
- Reward points
- Birthday offers
- Exclusive promotions
- Special shopping events
- Financing offers
- Free shipping
- Loyalty-program integration
The specific benefits differ substantially from one retailer to another.
What Are the Drawbacks of Comenity Store Cards?
Store credit cards can look appealing at checkout, particularly when a retailer offers an immediate discount.
But there are several disadvantages to consider.
High APRs
Interest rates can be high.
The Lane Bryant card’s current 35.99% purchase APR is a real 2026 example.
If you receive $20 in rewards but pay $80 in interest, the card has not saved you money.
Limited Use
A closed-loop card may only work with one retailer or family of brands.
That reduces its usefulness compared with a general-purpose rewards card.
Rewards Can Be Restrictive
Store rewards may:
- Expire
- Have minimum redemption requirements
- Work only at the retailer
- Exclude certain purchases
- Be subject to program changes
Another Credit Account To Manage
Every new card adds another:
- Due date
- Account balance
- Credit limit
- Statement
- Potential late-payment risk
A checkout discount alone is not always enough reason to open another credit account.
How To Choose a Comenity Store Card
Before applying, ask yourself several questions.
Do I Shop Here Regularly?
A retailer-specific card makes more sense if the store already receives a meaningful part of your spending.
Will I Pay in Full?
High APRs can erase discounts quickly.
Is There an Annual Fee?
Many retail cards have no annual fee, but verify the exact card.
Is the Reward Actually Valuable?
A $10 store certificate is not the same as $10 cash if you would not otherwise shop there.
Is Special Financing Available?
If so, understand exactly how it works.
Could Another Card Earn Better Rewards?
A general cash-back card may provide more flexible value.
How To Apply for a Comenity Credit Card
Applications are generally available through the associated retailer or official card-program website.
The typical process involves providing information such as:
- Full legal name
- Address
- Contact information
- Social Security number or other requested identification
- Income
- Housing information
Read the rate-and-fee disclosure before submitting the application.
Never apply through an unfamiliar website merely because it promises guaranteed approval.
How To Manage a Comenity Credit Card
Existing cardholders can typically manage their account through the appropriate online Account Center.
Depending on the product, users may be able to:
- View statements
- Check balances
- Make payments
- Review transactions
- Update account information
- Manage alerts
Bread Financial advises Comenity Bank and Comenity Capital Bank customers to use its official resources or the number printed on the back of their card for account support.
How Do You Pay a Comenity Credit Card?
Payment methods vary by account but commonly include online payments and other methods described in the cardholder agreement.
For example, Ulta currently directs cardholders to its online account-management system and also provides phone and mail payment options through Comenity Capital Bank.
Always use the payment instructions for your specific card.
Do Comenity Cards Help Build Credit?
A Comenity credit card can potentially help build credit when the account is reported to credit bureaus and managed responsibly.
The fundamentals are the same as with other revolving credit accounts:
- Pay on time.
- Keep balances manageable.
- Avoid unnecessary debt.
- Monitor statements.
- Pay more than the minimum whenever possible.
- Ideally pay the statement balance in full when no promotional financing strategy applies.
Do not open multiple store cards merely to build credit faster.
More accounts do not automatically mean better credit.
Do Comenity Cards Have High Interest Rates?
Many can.
APR varies by card and applicant.
For example, Comenity’s September 2026 general Mastercard agreement shows different possible purchase APR tiers, while Lane Bryant’s current agreement lists a 35.99% purchase APR.
Always check the Schumer box or rate-and-fee summary before applying.
That document is more reliable than an old blog post quoting a single APR.
Comenity Store Cards vs. General Cash-Back Cards
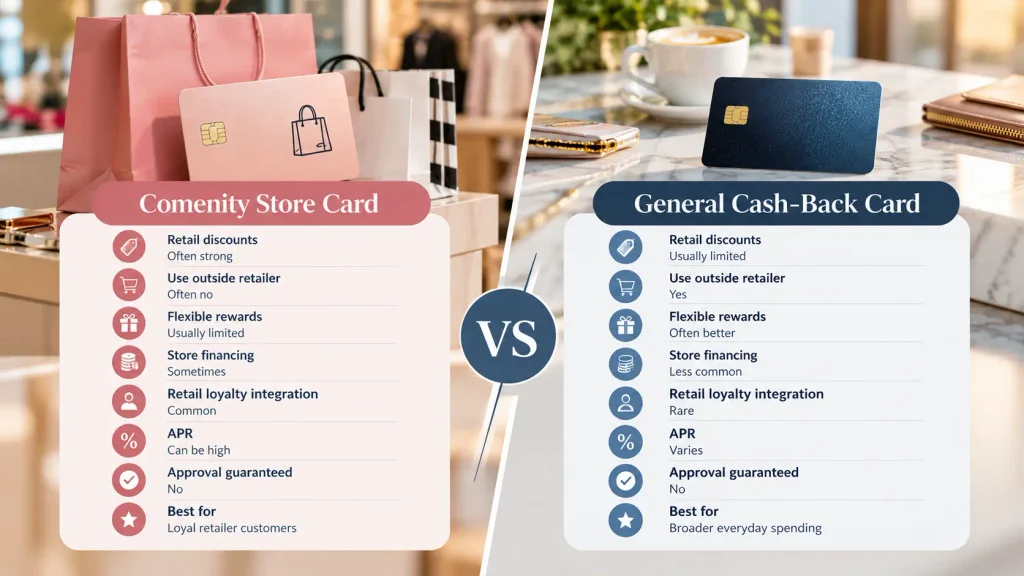
| Feature | Comenity Store Card | General Cash-Back Card |
| Retail discounts | Often strong | Usually limited |
| Use outside retailer | Often no | Yes |
| Flexible rewards | Usually limited | Often better |
| Store financing | Sometimes | Less common |
| Retail loyalty integration | Common | Rare |
| APR | Can be high | Varies |
| Approval guaranteed | No | No |
| Best for | Loyal retailer customers | Broader everyday spending |
Neither category is automatically superior.
The better option depends on spending patterns and how the account will be managed.
Common Mistakes To Avoid With Store Credit Cards
Store cards work best when shoppers understand the complete cost rather than focusing only on the checkout discount.
Avoid:
- Applying solely for a small one-time discount
- Assuming “easy approval” means guaranteed approval
- Applying for several cards in a short period
- Ignoring the purchase APR
- Carrying balances for rewards
- Misunderstanding promotional financing
- Confusing a store card with its Visa or Mastercard version
- Missing payment due dates
- Spending more just to earn retailer rewards
- Using outdated information about the card issuer
The upcoming Comenity bank merger makes that final point particularly relevant in late 2026.
Final Thoughts
Comenity Bank and Comenity Capital Bank remain major names behind U.S. private-label and co-branded credit cards in 2026, with programs spanning fashion, beauty, jewelry, home furnishings, automotive, entertainment, and other retail categories.
The most important distinction is between closed-loop store cards and open-loop Visa, Mastercard, or American Express products. A store card may deliver useful retailer-specific discounts and financing, while an open-loop card provides considerably broader acceptance.
Consumers looking for so-called “easy approval” cards should be cautious. There is no guaranteed-approval Comenity card, and the issuer does not publish one universal minimum credit score for its entire portfolio. Consider prequalification when available, apply selectively, and pay particular attention to APRs before carrying a balance.
Finally, 2026 is a transition year for the issuer itself. Bread Financial expects Comenity Bank to merge into Comenity Capital Bank around October 1, meaning card documentation and issuer references may change. Existing and prospective cardholders should rely on the current disclosures for their individual account rather than an older issuer list.
Frequently Asked Questions
Comenity Bank and Comenity Capital Bank have been associated with a very large portfolio of private-label, co-branded, and specialty credit products. The exact number changes as partnerships and card programs are added, discontinued, renamed, or transferred.
Bread Financial has received regulatory approval to merge Comenity Bank into Comenity Capital Bank and expected the merger around October 1, 2026. Comenity Capital Bank is expected to survive the merger.
Current programs include cards associated with brands such as Victoria’s Secret, Lane Bryant, J.Crew, KAY Jewelers, LOFT, Torrid, and others. Some programs are issued by Comenity Bank while others are currently under Comenity Capital Bank.
The Ulta Beauty Rewards Credit Card and Ulta Beauty Rewards Mastercard are currently issued by Comenity Capital Bank.
Some retailer cards may be accessible to a broader range of credit profiles, but no Comenity credit card guarantees approval. Underwriting varies by card and applicant.
There is no single publicly stated minimum credit score that guarantees approval across the entire Comenity portfolio.
Potentially. Approval depends on the individual card and your overall application rather than one credit-score category alone.
Some card programs may provide prequalification or pre-screening options. Check the individual card’s official application page and confirm whether checking eligibility affects your credit.
A formal credit-card application may involve a hard inquiry. Read the application disclosure before submitting it.
Some are, but many are not. Closed-loop store cards can generally only be used with the associated retailer, while Comenity also issues co-branded Visa, Mastercard, and American Express products.
Comenity Bank is part of Bread Financial.
They have historically been separate banking subsidiaries within Bread Financial. Bread Financial has received approval to merge Comenity Bank into Comenity Capital Bank, with the latter surviving the planned 2026 transaction.
They can potentially contribute to credit history when reported to the credit bureaus. Paying on time and keeping debt under control remain more important than the retailer printed on the card.
Usually, the better approach is to calculate the longer-term value. Consider the APR, shopping frequency, rewards, financing terms, and whether you would use the retailer without the card.